Archive for ‘Legal’ Category
How to Avoid or Minimize Probate: Trusts, Organizing Estate Information, and Helpful Resources
Previously on Paper Doll‘s “I don’t you don’t want to think about death but the paperwork is important” series:
- How to Avoid or Minimize Probate: Paper Doll’s Guide to Getting Started
- How to Avoid or Minimize Probate: Organize Your Beneficiaries, POD Accounts, & More
we looked at what probate is, how the process works, and the reasons why you want to avoid it as much as possible. Then we looked at two overarching categories (joint ownership and beneficiary transfers) for inexpensively and easily organizing your assets to avoid probate.
Today we’ll round out the options for avoiding or minimizing probate, clarify some issues regarding wills and their role in the probate process, detail how to organize your estate information to make the transition smoother, and share additional resources to ease estate planning.
WHAT IS A TRUST?
You’ve probably heard a lot of terms bandied about regarding trusts. Because (and I realize I’m repeating myself), I’m a professional organizer and not an attorney, we’re going to stick to the basics for educational purposes; this is not legal advice.
To create a trust, you’re going to need a lawyer’s assistance, which means it’s going to cost more money than the probate-avoiding methods we discussed last week.
Revocable Living Trusts
A revokable living trust is a stellar tool for helping you avoid or at least limit probate.
Think of a trust as similar to a suitcase or basket into which you place your assets. You transfer ownership of your assets — which can be tangible, like a house or a car, or intangible, like investments or bank accounts — into the trust. Instead of you being the owner of these assets, the trust owns them as a sort of spin-off variation of you. Think of it as the Trust of You.
The Trust of You is a completely separate legal entity from the actual walking-and-talking you, and once you transfer ownership, you don’t own your house (for example), but the Trust of You owns the house. It seems silly, but from a legal perspective, it’s powerful.
Throughout your life, you are the (initial) trustee, which means you still maintain total control over what happens to whatever assets you place in the trust. You can buy and sell stock in your portfolio, add a deck to the back of your house, or move money from your checking account to the savings account. It’s just all “owned” by a legal entity that is not you, but it’s controlled by you.
The key is that you name a successor trustee. The role is somewhat like the role of executor, except you don’t have to get the court involved or fill out a lot of excess paperwork. The job of the successor trustee is to follow your instructions for distributing the assets within the trust. That can mean parceling things out to the relatives and friends you’ve named, or the successor trustee may maintain ownership for their own lifetime, until it passes to the next successor trustee(s).
Trust Photo by Joshua Hoehne on Unsplash
When you set up a trust document (which the lawyer may call an instrument), you state:
- what property or assets are going into the trust
- who is the grantor (or settlor, or trustor), the person establishing the trust document
- who is the trustee, the person (or people) with the authority to manage the assets in the trust
- who is the successor trustee, the person who will distribute assets in the trust when you (or you and your co-initial trustee) depart the earth
- who are the trust beneficiaries, the individuals or entities who will receive the property after you’re gone
- and whether there are other trust terms, such as whether and how you can amend or revoke the trust.
You may also want to figure out what assets should be used to pay the eventual taxes on your estate.
With this document in place, you then “fill” the trust by transferring property from your name into the trust’s name.
So, your bank account will no longer be in the name of You, but the Trust of You; the deed to your house and the title to your car will be transferred from your name into the name of the trust, and so on. (Because random tangible assets like your fancy-pants jewelry and artwork (and your less fancy-pants possessions like, well, pants (and other clothing) — or furniture, or whatever — don’t have ownership documents, you can just list the property in the trust document as saying it’s owned by the trust.)
And everything that goes into the trust will be called the “corpus,” which is Latin for “the body” of the trust; you may also hear it called the trust estate, the trust property, or the trust principal. The point is, it’s your stuff until you (legally) drop it in that theoretical basket/suitcase, at which point the stuff belongs to the trust. Got it?
Once you shuffle (or tango) off this mortal coil, the successor trustee will need to:
- get a written verification of the market value of real estate held in the trust as of when the grantor (remember, that’s you) died. This is for tax purposes, because as you recall, the two things that are guaranteed are death and taxes.
- do paperwork to finalize the transfer of the assets in the trust
- give all of this trust information to the beneficiaries of the trust.
Why aren’t trusts subject to probate?
Because, from a timey-wimey, wibbly-wobbly, Jeremy Bearimy legal hocus-pocus perspective, technically, none of the assets inside the trust are yours.
Are they actually in a basket or a suitcase? Nope. It’s all just a hand-wave-y legal maneuver that lets the successor trustee transfer the assets from inside the trust to your heirs/beneficiaries without courts getting involved.
Not to sound like a three-year-old, but whyyyyyyyyyy can you do this? Because somewhere along the way, rich people agreed to make it easier on themselves, and now we non-rich people get to take advantage of the situation, too. Except, again, you’ll have to pay Lawyer Dude III, Esquire some money to get it all set up, so it’s not going to the be the first (or second) choice for many people looking to avoid the perils of probate.
Other than probate, what are the other advantages of a living revocable trust?
A revocable living trust is nifty because it provides flexibility. You can put anything in the trust, take anything out of the trust, do the hokeypokey and turn yourself around, because throughout your life, it’s under your control. Everything inside of the trust is yours to do with as you wish, aside from the fact that in (legal) name only, it doesn’t belong to YOU but the Trust of You.
It’s a living revocable trust, because it’s created while you are alive, and it’s a revocable trust because you can revoke it (that is, take it back, or revise the included property) as long as you are alive.
You can also maintain privacy. While a will becomes public record after probate, the terms of a revocable trust is private, both while you’re alive and after. Your financial holdings and your choices regarding how you distribute your assets will stay confidential!
Additionally, if you are alive but seriously incapacitated — if you suffer an illness or are injured — your successor trustee can act on your behalf to manage your trust assets, per your instructions. Remember last week’s example of the husband of the woman with dementia who would have needed a court-appointed conservatorship to sell a home owned in joint tenancy? That wouldn’t be necessary if they held their home in a trust.
The main thing to know is that setting up a revocable trust allows you to distribute assets smoothly, the way you want, without delays due to probate or fights among your beneficiaries.
What are the disadvantages of a living revocable trust?
- You have to fund the trust properly — If you don’t transfer the assets into the trust correctly, it’s as if you didn’t do it at all, and the assets will have to go through probate. (Lawyer! STAT!)
- Living revocable trusts don’t reduce estate taxes — There are no tax benefits to a revocable trust. (There are potential tax benefits to having an irrevocable trust, one that you can’t change during your life, but that’s too complicated for the purposes of this post.)
- You don’t have any asset protection — Because you have control over assets while you’re alive, creditors can sue and come after the assets. (This is another case where a irrevocable trust can offer extra protection.)
Who shouldn’t get a living revocable trust?
It might not be right in the following cases:
- If your property isn’t extensive, a trust may be unnecessary overkill. The methods we discussed last week may suffice, saving you time and money.
- If you don’t have someone trustworthy (like a spouse, sibling, adult child, or trusted friend, or relative) to oversee a trust after your demise, it’s not the best option.
- If you have oodles of debt, probate has the advantage of providing a cut-off date after which creditors can’t file claims against your estate. Living trusts don’t have any such cut-off date.
- If you’re worried about long-term care and Medicaid planning, an irrevocable trust may be a better option to protect you and your family.
What’s an irrevocable trust?
An irrevocable trust is like a revocable trust except that once the grantor (the one setting it up) transfers ownership of assets into the trust and funds it, nothing can be changed, revised, amended, or terminated, at least without a court order or the agreement of all beneficiaries.
So where does a will come in?
You may be wondering, if you’ve set up joint ownership, beneficiaries, POD/TOD accounts, deeds, and titles, and/or maybe even a trust, do you still need a will?
First, it’s important to know what your will can’t do.
ASSETS YOU CAN’T BEQUEATH BY WILL
A will controls property in your name, with no designated beneficiary and no automatic transfer mechanism. When you die, the will controls your probate assets. Your non-probate assets transfer by deed, title, contract, or named beneficiary.
The options we’ve discussed these past few weeks for easing probate prevent you from bequeathing the following assets by will. (Note: this is not all-inclusive. You daughter-in-law the cardiothoracic surgeon may be an asset to the family, but you can’t bequeath her to your best friend.)
- Life insurance policy proceeds for which you’ve already named a beneficiary
- Funds in retirement accounts, including pension plans, 401(K) plans, IRAs (of various types), or other retirement plans. Again, you just name a beneficiary.
- Money in a bank account designated as Payable on Death (POD)
- Stocks, bonds, and other securities held in beneficiary or Transfer on death form
- Real estate named in a Transfer on Death (TOD) deed
- Vehicles (and not just cars) held in beneficiary form, also called in Transfer on Death form
- Any assets or property you own in joint tenancy with your spouse or other individuals. As discussed last week, related ownership might be called tenancy by the entirety, like if you and your three college roommates buy a house, or community property with right of survivorship with your spouse or life partner. Remember, in such cases, your share of whatever your owned goes to the surviving co-owner(s).
- Assets/property that you’ve transferred to a living trust
Last Will and Testament Photo by Melinda Gimpel on Unsplash
EVEN IF YOU AVOID OR LIMIT PROBATE, YOU STILL NEED A WILL
It’s easy to think that if you set up beneficiaries for all of your securities, and set up POD status for your bank accounts, get TOD deeds for your house and car or set them up for joint tenancy with right of survivorship, and even have a revokable living trust, you can skip having a will. Don’t do that!
Wills are not just for distributing your goodies. They serve other purposes:
- If you have underage children or older dependent children with disabilities, you need a will to name a guardian (and provide guidance for that guardian). However, even if you don’t have children, or your kids are well established in adulthood, there are other reasons to have a will.
- If you acquire any assets after you set up your trust but before you revise it (or cease to exist), having a will and an executor means that you still have a say regarding how anything outside your trust gets distributed. This also helps if you get a gift or an inheritance that hasn’t yet gone through probate at the time you die, meaning you couldn’t have put it in a trust or named a beneficiary. In such cases, your will has a residuary beneficiary, a person named in the will to get everything else you own that isn’t left to any other beneficiary. And if you don’t have a will, state law determines where any of these “bonus” assets go. Do you want your state deciding something like this?
- If you have a small estate, a will makes the Small Estate Affidavit process that we discussed two weeks ago easier on your heirs.
WHY YOU NEED TO PLAN YOUR ESTATE
As you’ve seen from the past few weeks, as much as none of us want to think about death, avoiding the process may make us feel better in the short term, but it creates a lot of trouble for everyone we love after we depart. Here are some pretty compelling reasons to work through the issues.
Avoid an Unpleasant Treasure Hunt
Starting the process right now begins with finding the accounts, the investments, the insurance policies, the deeds, and the titles. Why make your executor waste time searching and waste money paying for documents you already have?
Keep the Wrong People from Becoming Heirs
If you don’t have a will that specifies who gets what, and you don’t name beneficiaries or do the paperwork for joint tenancy or setting up trusts, and you don’t keep all your paperwork annually monitored, the wrong people will end up being beneficiaries of your largesse.
Recently, a close friend’s sister-in-law died. Although her brother and his wife had been married for a few years, various situations kept her from prioritizing making a will, changing her beneficiaries, and even modifying her Power of Attorney documents for healthcare and finances. When she suffered a tragic accident, instead of her husband making the decisions for her care while she was alive, the duty fell to the relative she’d named as healthcare proxy before they’d ever married. Now that she’s gone, her estate will be distributed according to a combination of an out-of-date will and the decisions of someone else; her husband must either accept what happens or fight the executor’s decisions while still in the throes of grief.
If you don’t update wills, beneficiaries, and executor paperwork, the ex who cheated or the sibling who is no longer among us or the best friend who is no longer best will be granted power that you did not wish them to wield, or which they can no longer wield.
Of course, it’s not just money. The person you named to be guardian of your child(ren) 10 years ago may not be the person you’d want now.
Eliminate Confusion and Prevent Feuds
If you don’t plan your estate and keep everything updated, you leave people guessing about what you wanted. With uncertainty comes unpleasantness and infighting. That’s not the kind of legacy you want to leave.
Empower yourself and your loved ones by organizing your information so that you can make the best decisions about your estate plans and make it easier on your executor and heirs.
ORGANIZE YOUR ESTATE INFORMATION
The easiest way to make sense of all of the information you need to track is to create a spreadsheet of all of your assets.
Create a column for each piece of information for financial or tangible assets:
- Asset name — for example, “Personal Checking Account at Chase” or “Roth IRA”
- Account numbers for each asset
- Asset location — for example, the address of the property, the transfer agent for stock, the name of the life insurance company
- Contact information for the whoever manages the asset
- A description of whatever ownership documents you have
- The location of the ownership documents in your home, office, the cloud, etc.
- Beneficiary names — to whom you’re leaving each asset
- How the item is set it be transferred — by named beneficiary, POD, TOD deed, trust, etc.
- Other notes that might help clarify the asset for your executor and heirs.
For vehicles, make a separate spreadsheet with the following:
-
- each vehicle you own — remember to include those you own that others use, like your grandkid or housekeeper
- vehicle type (car, jet ski, golf cart)
- make
- model
- year
- vehicle identification number (VIN)
- location where it’s garaged (your house, a city garage, a storage facility) a barn or airplane hanger or marina berth)
- creditor information if you still owe
- location of the title, if you have received it after paying off any loans — If you’ve lost the paper title, apply for a replacement now and save your loved ones the labor and stress when they’ll already be mourning you.
- name of the Transfer on Death (TOD) beneficiary, if applicable
- location of any agreements, like a lease or garage/docking contracts
- location of the keys
Create a row at the top of the document with the date of revision.
Keep a printed copy of the most updated version of this document with your wills and other estate paperwork.
Revisit the document whenever you acquire new holdings, or at least annually to make sure:
-
-
- beneficiaries are still alive
- beneficiaries are still in your life
- documents, keys, and other essentials are still in the same place
-
RESOURCES FOR PLANNING YOUR ESTATE
For bank accounts, life insurance policies, securities, and retirement accounts, speak directly to the company that manages the accounts, and they will walk you through how to fill out the beneficiary forms we discussed last week. For real estate and other tangible items owned in joint tenancy, start with your local county clerk’s office to see whether you can download templates or if you’ll need to consult an attorney.
Professional Organizers can save you time and headaches, locating all of your documents and organizing the information. You may also find it beneficial to speak with a Daily Money Manager.
If someone in your family has already passed and you’re needing additional help, another resource is Professionals of After Loss Services (PALS).
My colleague Seana Turner blogged about Connecticut-based Transference, a company that specializes in helping executors, surviving family members, and overwhelmed Power of Attorney-holders handle financial and legal logistical challenges.
Get Your Sh*t Together (GYST) — This site offers a wealth of advice, checklists, and free templates to help manage all of the details related to completing your estate planning documents, including The Get Your Sh*t Together Essential Checklists.
Ellis Family Guides — Four free, directly downloadable books on getting your affairs in order, living trusts, Social Security and Medicare, and wills, trusts, and estate planning. They require no sign-ups; you don’t even have to provide your email address unless you want to receive an annual email with updated Social Security and Medicare figures.
Estate Exec — This site describes itself as the estate settlement equivalent of what Quicken does to help manage finances. The software promises to walk you step-by-step though all aspects of an estate, with checklists and record-keeping features. It also grants log-in access to the estate’s account to desired interested parties. They have a ten-day free trial requiring no credit card, email, or registration; if you choose to keep it, it’s a one-time payment of $199 per estate, which is deductible as an estate expense.
NOLO Estate Planning Basics by Denis Clifford ($21 on Amazon)
NOLO’s Executor’s Guide: Settling a Loved One’s Estate or Trust ($25 on Amazon)
Childfree Trust — This fascinating newcomer bills itself as the “only comprehensive, nationwide estate solution for Childfree and Permanently Childless people.” They help you create estate documents and promise to be “your professional, fiduciary medical and financial POA, executor, and trustee and ensure your wishes are followed as you wrote them.” They offer members a 24/7 emergency support call center. It’s free to create an account, but membership costs $999/year with locked-in discounts for prepaying for two or three years.
After three weeks of reviewing what probate is, how to avoid it, and how to organize your estate information to ease the process, I hope you’re finding this essential aspect of “adulting” to be a bit less intimidating.
How to Avoid or Minimize Probate: Organize Your Beneficiaries, POD Accounts, & More
Nobody likes thinking about death, but as Benjamin Franklin said, “[I]n this world, nothing is certain except death and taxes,” and as such, we’re better off being organized for the eventuality than trying to wish it away.
Last week, in How to Avoid or Minimize Probate: Paper Doll’s Guide to Getting Started, we began by looking at the essentials: what probate is, how the process is started and then progresses, and then the alternative use of Small Estate Affidavits. Perhaps more importantly, we reviewed (in depth, as only Paper Doll can do), why you want to avoid probate whenever possible, in order to:
- lower (considerable) costs
- save time
- maintain family privacy
- ease the stress felt during a time of mourning
Now clear on why you want to avoid probate, or at least minimize it as much as possible, we come to the heart of the matter. What do you actually have to do to avoid the pains of probate?
HOW DO YOU AVOID PROBATE?
Whether she realized it or not, my maternal grandmother had an interesting way of making sure that probate would be as unproblematic as possible. If you came to her home and managed to praise anything — a teacup, a lamp, a painting — she would hand it to you at the end of the visit!
Giving everything away during your lifetime is an intriguing approach, but not necessary practical. Also, while it reduces what has to go through probate, if you’re giving actual money, remember that gifts exceeding $19,000 per person are subject to federal gift tax.
Rather, there are three main methods for securing assets so they go from your ownership to those you intend to receive them — avoiding probate — without ever pressing an oversized ceramic dog statue into a departing guests hands.
The three categories actions you can take to avoid probate:
- Own assets jointly
- Name a beneficiary through a beneficiary transfer form, Payable on Death form, or Transfer on Death form
- Create a revokable living trust (RLT) in which the trust is the owner of your “stuff” and can be passed to named beneficiaries
Again, as a reminder, Paper Doll is a Certified Professional Organizer® and not an attorney. Nothing in this post series is, or should be taken as, legal advice. Rather, it gives you a jumping off point for approaching the appropriate parties (at your bank, brokerage, insurance company, county government, or your actual attorney) with your wits about you.
Today, we’ll focus on the first two (easier) categories of getting assets into the hands of your loved ones while avoiding probate.
ARRANGE JOINT OWNERSHIP
If you own something (a bank account, a house, a chestnut-colored thoroughbred horse) all by yourself, you have to take a variety of steps to ensure that when you shuffle off this mortal coil, it goes to whomever you wish.
However, if you jointly own something, when one owner passes away, ownership passes to the other owner(s) in a straightforward way. Let’s start with a simple example — bank accounts.
Joint Ownership Bank Accounts
A joint bank account is one jointly owned by two (or more) people. Duh! Most commonly, people open joint bank accounts when they get married so that they can pay for joint expenses, such as mortgages, utilities, household upkeep, childcare, family vacations, etc.
Marriage or cohabitation isn’t the only reason you might have joint ownership of a bank account.
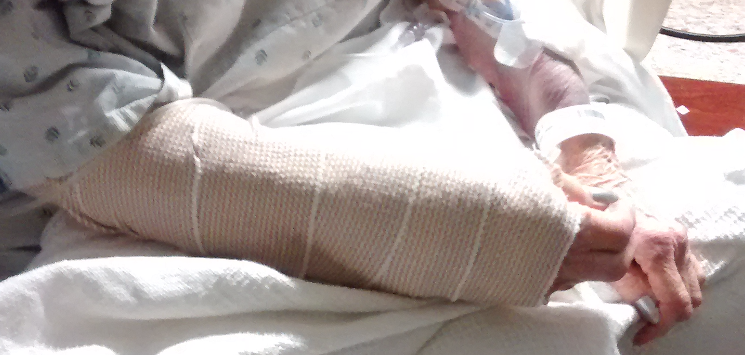
Paper Mommy, wrist in a cast, but with a perfect manicure, 2016
Almost a decade ago, when Paper Mommy broke her wrist, I took over paying her bills by phone; however, the next time I visited Buffalo, we went to her bank so set up checkwriting access for me and for my sister, and my mother found that it made sense to add us as joint holders of the account.
If you set up joint ownership (either when you open an account or subsequently), and then pass away, your joint accountholder(s) will have still access to the funds in the account. They won’t have to present a death certificate to the bank until/unless they take your name off the account, at any future time.
This is a great option for seniors, assuming they’re comfortable with the other joint accountholders (like their adult children) always having access to the money. Obviously, it’s necessary to consider the maturity, stability, and trustworthiness of anyone named as a joint account holder.
Joint Tenancy
Joint tenancy is a probate-avoiding method of owning assets, commonly focused on real estate. When one owner (the “joint tenant”) passes away, the other, surviving joint owner(s) will automatically inherit the portion owned by the person who died, through a legal status known as “right of survivorship.” If you survive — that is, live beyond the time that co-owner ceased to do so — you have the right to own their share.
Little Red Houses Photo by Tierra Mallorca on Unsplash
It’s not magic; there’s paperwork to transfer the property into the name of whomever inherits, but for all practical purposes, this right of survivorship makes it easy to transfer real estate — houses, condos, farms, etc. — without the stress of probate. Joint tenancy can be used to transfer ownership for assets other than real estate, like car titles or a bank accounts, as described above, but let’s keep this simple.
When you buy property or set up ownership, make sure the deed, title, or other paperwork establishes joint ownership, usually by referencing “joint tenancy with the right of survivorship,” though a few states require a little bonus language.
In most U.S. states, joint tenants own equal shares. So, if Ernie and Bert co-own the brownstone at 123 Sesame Street, each owns 50%. (Of course, neither Ernie nor Bert will EVER pass away, so this is merely for discussion purposes. Are we clear? Let’s proceed.)
A joint tenant can’t leave their share to anyone but the other joint tenant(s). So, Ernie can’t stipulate in his will that his share of the brownstone goes to Grover; if Ernie ever did ascend to the great unknown, Bert would own the whole building.
Joint tenancy, especially with real estate, does have some drawbacks:
- Creditors can sue for your joint tenant’s portion. If you jointly own a house with your deadbeat boyfriend, the court could force the sale of the house to reimburse his creditors; you’d get your share of the money (while some or all of his share would go to the creditors), but you’d no longer own your home or have the full buying power that house represented. The other joint tenant can also take out a mortgage on their share to get cash, so you’d now own a house half-owned by the bank!
- You can’t unilaterally un-share ownership. If darling becomes a devil, you’re still bound to them.
- You’re stuck if your joint tenant becomes incapacitated. If a couple own a house in joint tenancy and the wife suffers from dementia, the husband can’t just unilaterally decide to sell (or take a mortgage) to afford assisted living for her. Instead, he’d have to get conservatorship from a court. Messy.
Tenancy by the Entirety
Tenancy by the Entirety (TBE) is very similar to joint tenancy, but it’s only available to married couples.
The other major difference is that neither spouse can sell or otherwise transfer ownership of their half of the property during the lives of the either spouse without the other’s permission.
It’s also only allowed in some states, and for some inheritance purposes. Tenancy by the entirety is possible for:
- All property types (i.e., real estate and personal property) in Arkansas, Delaware, Florida, Hawaii, Maryland, Massachusetts, Mississippi, Missouri, New Jersey, Oklahoma, Pennsylvania, Tennessee, Vermont, Virginia, and Wyoming, and in the District of Columbia
- Real estate only in Alaska, Indiana, Kentucky, New York, North Carolina and Rhode Island.
- And in special situations:
- Illinois — it’s limited to married couple’s primary residence, called a homestead property.
- Michigan — all joint tenancy situations are automatically converted to TBE status upon a couple’s marriage.
- Ohio — TBE is only recognized for property deeds issued before April 4, 1985.
- Oregon — both spouses own the entire property rather than each holding a 50% share
TBE is complicated; get an attorney to help you with estate planning because it can impact a variety of issues, including creating trusts, planning gifts, or Medicaid lookbacks.
Community Property With Right of Survivorship
Miniature Couple Photo by Nothing Ahead
Nine states — Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin — are considered community property states for married couples. (California and Washington allow registered domestic partners to do this as well.) Basically, it’s “what’s mine is yours and what’s yours is mine” such that when one spouse dies, the ownership of their community property automatically goes to the surviving spouse.
In these community property states, you can avoid probate by putting “community property with right of survivorship” (or an approximate phrase) on any account registration paperwork, deed, or transfer documents. Check for the exact language your state requires.
Joint ownership can be complicated. Let’s examine variety of alternate ways to transfer ownership that cost little-to-nothing, and require so little effort that you’ll think you’re gaming the system.
BENEFICIARIES / PAYABLE ON DEATH / TRANSFER ON DEATH
You know what a life insurance beneficiary is. You take out a policy, name someone as the beneficiary, and when you’re gone, the proceeds go to the named person. But the concept of beneficiaries can be applied to much more than life insurance!
The key thing to know about these options is that everything belongs to you and stays under your control during your life. Whether an investment or retirement account is listed as having beneficiaries, or a bank account or asset is categorized as Payable on Death or Transfer on Death (TOD), beneficiaries don’t have access until the owner of those assets dies.
Payable-on-Death (POD) Bank Accounts
You can name an individual (or individuals) to inherit money from a bank account when you pass away. The difference between a jointly held account and a payable on death account is that with the former, you all have access to the money at any time; with a POD account, you name individuals who get your money after you’re gone.
Arrange this when you open the account or at any time thereafter. While it’s not difficult, every bank has its own procedures, so be sure to ask.
Rather than calling, you’ll likely have more luck going to your actual branch and asking one of the “desk ladies.” (This is how Paper Mommy and I refer to a non-cashier bank employee with a desk or office. Yes, a man can be a desk lady.) While researching this post, I tried calling Paper Mommy‘s bank branch, but nobody ever answered. Eventually, I called the toll-free number, and after suggesting they check to make sure my mom’s branch wasn’t being robbed (yes, I watch too much TV), I was able to confirm some aspects of the process.
Some banks make it very easy. With Bank of America, you can log into the app, click on the three horizontal lines in the top left corner, select Profile, then Settings, and scroll down to the Beneficiaries option under Feature Settings.
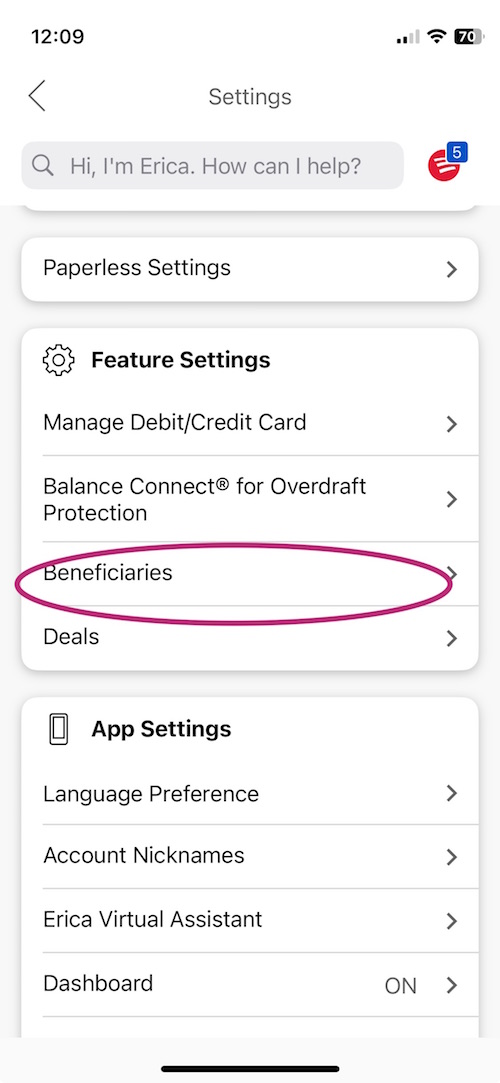
The resulting “Your Beneficiaries” page shows all of your accounts:
- Pick an account
- Click “Add beneficiary”
- Choose the beneficiary relationship:
- Spouse, family member, or friend not on the account, or
- Business, charity, estate, or trust
- Fill in the beneficiary’s full name, birthdate, country of citizenship, and current address or tax ID (Social Security number or EIN)
- Click Save
I accomplished the whole task during one commercial break! However, some banks make it slightly more laborious. Plan to follow some approximation of these steps:
- Go to your bank’s branch. It’s often best to schedule an appointment through your banking app.
- Ask the banker to change your account’s designation to Payable on Death (POD). Note that your bank may call this something else, like:
- Informal Revocable Trust — Unlike formal revokable trusts, which are established by written trust agreements (requiring lawyers and lawyers’ fees), an informal revocable trust account works just like setting up a beneficiary for an insurance policy or investment holding. When the account-holder dies, the “deposit” (that’s the account) “passes” from the owner directly to the beneficiary/beneficiaries without the need for any written trust agreement.
- Totten Trust
- Beneficiary
- Transfer-on-death (TOD) or In Trust For (ITF) or As Trustee For (ATF)
- Provide the following for each beneficiary:
- Full legal name
- Residential address
- Phone number
- Date of birth
- Relationship to you
- Set your intended allocation. The default allocation divides the account balance equally among all beneficiaries still alive when you die.
- Confirm that your signature card is on file.
- Review the form for accuracy and sign it.
If you use an online-only bank, call but be prepared to explain (a few times) what you want and know that you’ll likely have to upload proof of identification to a secure portal.
Once a person dies, the beneficiary can just go to the bank, show the death certificate and their own proof(s) of identify, and obtain the funds.
Advantages of POD Accounts
You avoid probate!
It’s also relatively simple and and cost-free, not counting the value of your time. You don’t need a lawyer; just go to your bank or credit union, fill out the POD paperwork, and you’re set.
POD accounts are revocable. If your one of your kids becomes a meanie, or your sibling becomes a candidate for a political party that turns your stomach, just go to the bank with an explicit written revocation — or just withdraw all the money from the account, close it, and open a different account.
Limitations of POD Accounts
A POD account only applies to bank (or credit union) accounts, like bank deposit or checking accounts, savings accounts, or certificates of deposit (CDs); you can’t set up this kind of POD for real estate, stocks and bonds, or physical property like cars or boats or your Beanie Baby collection.
Even though it might be called an informal revocable trust, it doesn’t safeguard money from creditors the way a trust does. While you’re alive, if you owe personal debts, creditors can still make claims against whatever money is in that account.
Transfer on Death (TOD) Registration of Securities
Per the Uniform Transfer-on-Death Securities Registration Act, you can name someone as the beneficiary of your stocks, bonds, mutual funds, or brokerage accounts. This is known as Transfer on Death or TOD.
You’re likely already familiar with how this works if you’ve ever set up any kind of standard investment account, as listing beneficiaries is generally part of the basic paperwork. Just provide the individual’s name and Social Security number, plus some contact information and you’re done. When you die, the assets in that account will pass to your beneficiaries once the financial institution is notified of your passing.
That said, it’s important to periodically check your beneficiary listings. If you name your spouse as beneficiary and have an acrimonious divorce, or even an amicable one but then remarry, you’ll want to change that beneficiary paperwork. Also, as the years go by, not all beneficiaries may still be alive; if someone passes, update your beneficiary names!
While you aren’t required to list beneficiaries, if you don’t do it, all of your investments will just sit in your account upon your death, going nowhere until your will goes through probate. And without a will, your loved ones will have to wait even longer for everything to be resolved.
You can generally name anyone as beneficiary of your securities investments: a parent, spouse, child, sibling, distant relative, friend, George Clooney — even a business or non-profit/charity. You can also name your trust as the beneficiary.
Note: You may be limited by state property law. Remember those community property states? There, you must get your spouse’s signed, witnessed consent to designate anyone other than your spouse as your primary beneficiary for a TOD for securities.
Retirement Accounts
Retirement Beach Photo by Costa Karabelas
You worked hard for your retirement benefits, so make sure that money goes where you want. When you set up any kind of retirement account — a pension plan, an IRA (of any kind), or a 401(K) — you’re required to list a beneficiary, usually a primary and secondary one.
Whether you live in a community property state or not, you’ll need spousal permission to list anyone except your spouse as your beneficiary.
Again, this isn’t entirely set-it-and-forget-it. People change spouses. Friends and relatives pass away, or just out of our lives. Businesses close or change ownership and charities don’t always maintain their mission. Periodically review your beneficiaries and make changes if necessary.
As with securities, retirement accounts live up to the concept of a TOD designation — they get transferred upon (proven notification of) death. When a you die (eons from now), your beneficiary should contact the retirement account custodian — that’s the financial institution that holds the account’s investments, processes the transactions, keeps all records, documents incoming contributions and outgoing distributions, and oversees the reporting to the IRS and other government agencies, as required.
Your beneficiary should provide a death certificate and their own ID, and then claim the funds directly or transfer the account into their own name(s) so they can maintain those investments, either as-is, or adding/revising the assets in them, just as if they’d opened the account themselves.
Transfer on Death Deeds for Real Estate
In 31 states and D.C., you can avoid probate on real estate by creating a Transfer on Death deed. Those states are: Alaska, Arizona, Arkansas, California, Colorado, Georgia, Hawaii, Illinois, Indiana, Kansas, Maine, Minnesota, Missouri, Montana, Nebraska, Nevada, New Hampshire, New Mexico, New York, North Dakota, Ohio, Oklahoma, Oregon, South Dakota, Texas, Utah, Virginia, Washington, West Virginia, Wisconsin, and Wyoming.
Also, in Florida, Michigan, Texas, Vermont, and West Virginia, a Ladybird Deed, (also called an enhanced life estate) allows Medicaid beneficiaries to protect their home from the Medicaid Estate Recovery Program and pass the house to a loved one as inheritance, rather than to a state Medicaid agency to reimburse long-term care costs.
- Complete the deed — Depending on the state, homeowners may be able to access a free deed template; look for downloadable forms on your county or state website. Otherwise, an attorney can prepare your Transfer on Death deed. The TOD deed requires:
-
- your name and personal information
- a legal description of the property — a single family home, a condo, or a banana stand?
- the beneficiary’s full name and address
- the beneficiary’s relationship to you
- Sign the deed and have it notarized — Legal lingo: you’re the transferor and must sign the deed, but your beneficiary does not need to sign it.
- File it with your county’s land records office — Don’t leave it sitting in a pile on your microwave, because if you die before it’s officially filed and recorded with the governing authority, it’s invalid.
Note: The deed must state that it won’t take effect until your death and that it is revocable by you at any time prior to your death.
Revoking a TOD deed
Speaking of which, as with almost all of these options today, you can revoke your transfer on death deed altogether, or change your beneficiary. Just file a revocation, a written document starting you want to revoke the terms of the beneficiary deed you’ve previously made and recorded (that is, filed).
States vary, so if you were able to download a form to file, look online for a downloadable revocation form. (Some states have sample revocation language in the statutes that legalized TOD; copy that language.) File the revocation at whatever governmental office where you filed the original TOD deed.
You may have to pay an attorney if your state requires a grownup to prepare the document. You also may have to pay a filing fee.
Thus, unlike setting a beneficiary for your bank account, securities, or retirement account, TOD deeds are neither super-quick nor always inexpensive. However, they’re much quicker and less expensive than going through probate.
For those who live in a state not listed above, the best option for avoiding probate is to place your home or other real estate in a trust, which we’ll discuss next time.
Transfer on Death Registration for Vehicles
Got a car? (Or a truck, motorcycle, boat, RV, jet ski, snowmobile, tractor, or airplane?) You may be able set up a TOD registration so that when you die, ownership will pass directly to whomever you wish, avoiding probate.
Little Red Car Photo by Gimmel Magaway on Unsplash
Vehicles are generally registered in the name of one owner, though it can be more than one in the case of co-owners, as we discussed with joint tenancy, above. However, in 15 states (Arizona, Arkansas, California, Colorado, Connecticut, Delaware, Illinois, Indiana, Kansas, Missouri, Nebraska, Nevada, Ohio, Vermont, and Virginia), contact your state’s department of motor vehicles and request a copy of your “car title in beneficiary form.”
Once you register the vehicle, the title certificate will not only list your name as owner, but also the beneficiary you choose. After your death, they go to the DMV with the death certificate and ID, fill out the new title, and pay a transfer fee (ranging from $15-75).
While you’re alive, nothing about naming a beneficiary on the Transfer on Death registration form impacts your ownership. You can sell it to the teenager next door or donate it to 1-877-Kars4Kids. If you get annoyed at your beneficiary for playing bad music on the car radio, just name a new/different beneficiary.
Residents of the other 35 states (and DC) have limited alternatives. Your state may have TOD systems limited to surviving spouses or one’s that apply only to low-value vehicles. Contact your state’s Department of Motor Vehicles to find out what your options are.
As this series continues, we’ll look at setting up trusts and assets you can’t bequeath by will.
We’ll also look at how to organize information about your assets to make things easier for your loved ones, and provide resources for asset-holders, executors, and beneficiaries.
How to Avoid or Minimize Probate: Paper Doll’s Guide to Getting Started
October 19-25, 2026 is National Estate Planning Awareness Week. In 2008, Congress established this as an annual event, in part because so many Americans do not have wills or other estate documents, and often do not understand the elements involved.
We’ve previously talked about important documents to have when someone is alive, in case of emergency, like a:
- Power of Attorney
- Healthcare Proxy
- Advanced Care Directive or Living Will
To refresh your memory on these documents, see past Paper Doll’s classic post How to Create, Organize, and Safeguard 5 Essential Legal and Estate Documents.
Most people understand how these are used during someone’s life. However, there is often confusion as to how things will work after a death.
Recently, while organizing a client’s vital documents, I asked some general questions regarding the basics of the paperwork: filling trusts, naming beneficiaries, changing the status on accounts, etc., and the client said, “Thankfully, we don’t have to worry about any of that. I have a will!”
The reading of the will in Monseiur Verdoux (1947), in the public domain
If you watch old movies about such things, there’s usually a death, a sobbing person falling to their knees, a funeral, and then a formal reading of the will, at which point a portly lawyer turns the assets over to whomever is there — loved ones, a mysterious woman in a veil, a beloved dog. In movies, after a few shocking disclosures, everyone leaves the room owning what they were bequeathed.
Yeah, no. That’s not how it works.
In most cases, assets are transferred from the person who is deceased to the new owner(s) in one of two ways, either through a process called probate or as the result of specific probate-avoiding actions, like setting up trusts, joint ownerships, or direct transfers (like registering an asset as Transfer-on-Death or Payable-on-Death).
Over the next few posts, we’re going to cover these concepts, including how to properly set up accounts, ownership, and beneficiaries of assets to reduce the emotional and financial stress on those who are left behind.
WHAT IS PROBATE?
You’ve certainly heard about probate before. You know it has something to do with wills and what happens when someone dies, and that may be the limit of your familiarity.
Most adults who haven’t ever dealt with probate tend to nod sagely when someone else is discussing it, and hope nobody will ask them questions. (In that way, it’s similar to being in an algebra class. Look interested, but not so interested that anyone will ask you to weigh in.) Don’t let embarrassment or uncertainty lead you to miss out on the opportunity of easing the entire process.
In the simplest terms, probate is a legal process where a court supervises the distribution of the assets of a deceased person.
Probate exists because no matter what the will says about who gets what, the government (under the guise of the probate court) has a vested interest in making sure that all of the estate’s debts (if there are any) get paid off before any heirs collects assets. The court also needs to make sure that taxes are paid and that assets are properly transferred.
Probate doesn’t only happen when there’s a will. If someone dies intestate — that is, without having left a will — and there are interested parties (heirs), an estate usually goes through the probate process as long as the value of the personal property of the estate (not counting a house or other types of real estate) is above specific dollar value.
Plus, if someone does die without a will, the probate code determines who gets what. That means, for example, if someone dies while going through a nasty divorce but doesn’t have a will, the court will give a lot of their assets to the not-yet-ex instead of to the non-profit or beloved friends they might have wished to receive those things.
How To Start Probate
As a reminder, Paper Doll is a professional organizer and not an attorney, so nothing in this post series should be taken as legal advice. Rather, it should serve to give you a better understanding of what to expect when you organize your important documents and information to make the estate management process easier.
- Name an executor — The testator (that’s the person making the will — also known as the last will and testament) names an executor, the person who controls someone’s assets after death, carries out the deceased’s wishes, and distributes the assets. The executor can be a spouse, an adult child, a friend, or even an individual hired for the purpose.
- Submit the will to the probate court — The executor submits the original, signed will to the office of the probate court clerk in the county where the deceased person lived. So, if Great Uncle Phil lived in Polk County, Iowa but you’re his executor and you live in Hawaii, you’ll need to submit everything to Polk County.
- Submit a certified copy of the death certificate to the probate court clerk’s office. Typically, the funeral home will provide the family of the deceased with multiple copies of the death certificate. You can always get more from your state’s Office of Vital Records.
- Fill out a sworn petition to probate the will — The word “petition” is just a fancy legal term for request or application. The petition form will include information about:
- the testator (again, that’s just the deceased)
- an estimation of the total value of their assets — Later in this series, we’ll talk about how to organize that information so the amount submitted can be accurate.
- the names, addresses, and relationships (to the deceased) of anyone named in the will, or if there is no will, the same information for any relatives who might be entitled to inherit.
Note: in some counties, the petition to probate a will has to be drafted and filed by an attorney, so check with the Probate Court Clerk before trying to use or submit any online forms on your own.
Probate Lawyer Scrabble Photo by Melinda Gimpel on Unsplash
The court will charge fees for the probate process; if you have to hire an attorney, there will be fees for that, too. Know that that all estate-related fees can be paid (generally, reimbursed) from the deceased assets.
What Happens Next
Once you file all the paperwork with the probate court, you’ll be schedule for a hearing in front of a probate court judge. Unlike anything you’ve ever seen on Perry Mason or Law & Order, this is not likely to have much dramatic effect. Assuming nobody objects to the person named as executor, the judge will officially appoint the named person to do it.
If there are objections (let’s say Big Brother and Little Sister have a longstanding beef), the judge may name a more neutral party, like an attorney, to serve as the executor. Either way, whoever takes on the role with make an oath to “faithfully” pay the owed debts and distributed whatever assets are left over according the wishes the deceased expressed in the will.
The Executor’s Role
Next, the judge will give the executor a legal document called Letters Testamentary, and yes, it sounds like something out of an 18th-century English novel. Just go with it. In some jurisdictions, it may be called letters of administration. It’s just a document authorizing the executor to act on behalf of the estate.
Again, it’s a legal document. Don’t fold it into quarters and stick it at the bottom of your purse with the half-eaten bag of gummy bears. Don’t clip it to the sun visor of your car. Make a folder for it and put in the VIP (very important paper) section of your filing cabinet. Scan it and keep a copy on your phone so you can refer to it when aren’t at your home or office.
One of the rights of being an executor is actually an obligation: to withdraw all the money from the deceased’s bank accounts and then deposit it in a new account for the estate. This way, the executor can pay the debts and distribute any financial assets to the heirs.
Once the executor has notified all creditors, paid all debts and/or filed objections to creditors’ claims with the court, and distributed the assets, the estate can be closed. This involves filling out and signing a form documenting all payments made from the estate and sending it to all beneficiaries named in the will. If everyone gives the okey-dokey and feels the accounting is correct, they also sign the form. Finally, the form gets submitted to the probate court judge for approval and the estate can be officially closed.
Can you see the advantage of organizing your assets so that your estate can avoid, or at least minimize, probate?
SMALL ESTATE AFFIDAVITS AS AN ALTERNATIVE TO PROBATE
A small estate affidavit isn’t the deed to a tiny house.
“Small estates” are those valued at a relatively low amount. Heirs can collect the assets/property without going through a formal probate process by securing something called a Small Estate Affidavit.
Depending on the state, that “small” amount may be $10,000-$25,000, like in Alabama, Georgia, New Hampshire, and Vermont, or it could be what some of us would not consider small at all, like $150,00-$400,000 in states like Arizona, California, and Wyoming. Most states fall somewhere in the middle. For example, in Tennessee, where Paper Doll resides, the limit is $50,000.
There are usually special requirements for filing small estate affidavits:
- the assets must have been owned solely by the deceased. That means that jointly-held assets don’t count.
- real estate is excluded. Almost all states deny the transfer of real estate to heirs via a small estate affidavit.
- there are waiting periods after the date of death. Almost all states require you to wait some amount of time, generally 30-45 days, before the affidavit can be obtained.
- your executor or proxy will have to get their signature on the affidavit notarized.
There’s an additional hiccup with small estate affidavits. During the normal probate process of a well, the probate court determines if there are creditors owed anything for the deceased’s outstanding deaths and makes sure they get paid.
Because there’s no parallel process with small estate affidavits, the individual filling out the affidavit generally has to report any known debts and take responsibility for them. This is why many people who could avoid the costs and effort that probate entails don’t seek this alternative.
It can also just be a bother. Earlier this year, I found that one of my clients was receiving mail at her address regarding two sets of stock holdings in the name of her deceased father. Although he had a will for which my client was the executor, by the time he died (about five years earlier), the family had not known/felt that he had any assets making the probate process with it. He’d arranged for joint ownership of bank accounts, and no longer owned property, as he was living in a nursing home. At the time of his death, the two stock holdings weren’t at the forefront of anyone’s mind.
Had my client’s father named her (or anyone) as a beneficiary for those stock holdings, she could easily have transferred the funds by supplying a copy of the death certificate. However, because he had never named a beneficiary, my client had to jump through several hoops in order to secure (and pay for) a small estate affidavit, submit it to the stock transfer agent, transfer the account ownership to her name, and finally arrange to sell the stock and receive the proceeds. It took time and effort (for both of us) and money just to ensure a transfer of assets reflecting what his will had originally stated — than anything of his was to go to his daughter.
As you can see, not planning ahead can be a headache for loved ones left behind.
WHY YOU WANT TO AVOID PROBATE
I don’t mean to scare you. The emotional weight surrounding death, either of a loved one or of all of our eventual shuffling off this mortal coil, is heavy. Rather than add the unwanted (and unexpected) weight of the financial and legal aspects of passing, it’s better to get to know and understand the big picture so that you can take actions early enough to smooth the entire process.
So, why avoid probate or at least lessen the complexity?
Lower Costs
Probate can be pricey!
Attorney fees, executor fees, appraiser fees and notary fees all add up. Executors can’t always be expected to donate all of the time necessary to accomplish probate tasks. And, sad to say, courts don’t run on good vibes. If you go through probate, you’ll likely have to shell out for:
- Filing fees — While they vary by state and county, most initial filings costs between $200 and $500 for a standard probate petition filing.
- Attorney fees — Probate attorneys generally charge hourly fees, and an “easy” probate may take 30+ hours at anywhere from $200-$500/hour; alternatively, attorneys may have flat package fees for uncomplicated probate. Note, however, some states have statutes governing attorney fees as a percentage of the estate’s gross value. For example, in California:
- 4% on the first $100,000
- 3% on the next $100,000
- 2% on the next $800,000, and
- 1% on the next $9 million!
- Executor fees — Executors have a right to compensation. While family members may choose note to charge the estate for their labor as executors, they have the right to do so. Plus, in states that have statutory attorney fees for probate, executors are due equivalent payment as a percentage of the estate’s gross value.
- Appraiser fees — In order to determine the fair market value of assets, appraisers bring their expertise to the valuation of everything from real estate and businesses to jewelry, antiques, artwork, and collectibles. And appraisals are usually required as part of the formal inventory of an estate’s holdings.
- Accountant fees — If an estate generates income (like from rent, dividends, interest, or business holdings), someone has to prepare the the taxes!
- Notice and publication costs — Executors incur costs for mailing formal notices to creditors and publishing notices to creditors.
- Certified copies of court orders — While these are small charges, generally from $5-$25 per copy, the executor will need several copies to show title companies, banks, transfer agents, and other financial institutions.
The more fees there are, the less value remains in an estate. If you’re Scrooge McDuck with oodles of gold, it may not make a material difference, but for most people, keeping costs down is essential.
Why let an estate’s value be eaten up and depleted by fees you can avoid?
Save Time
Even in the best of times, probate can take months — sometimes years — to work its way through the courts. During the early COVID pandemic, courts were closed, and once they re-opened, with so many employees working from home without access to physical documents, the process was extended.
Even in normal times, during certain seasons the courts slow down as staffers are on vacation and during holidays. It’s not uncommon for it to take months just to get a probate court hearing date in large metropolitan locations.
In addition to court backlogs, probate can be slowed by other factors, like:
- Mandatory creditor notice periods — States requires executors to notify any creditors and potential creditors and provide a window (often 3-6 months) in which to file claims against the estate. (Creditors, like credit card companies, are easy to notify. Other potential creditors may be unknown, so it’s common to post in the classifieds of Penny Saver newspapers, even almost nobody reads them.) Even if the estate doesn’t have any debts, that notice period is obligatory, and the executor can’t distribute any assets until the window closes. The process is really complicated and varies by state, debt type, and method, so if you’re eager to learn more take a peek at Probate Notice to Creditors and Claim Deadlines by State, and then maybe take an aspirin.
- Sales of real estate and other property required by a will or to satisfy debts — And it’s not just the sale. A property first needs to be appraised, and then it may need to be maintained/remodeled/made “safe for habitation.” If the property wasn’t covered by insurance at the time of death, it must get covered before the property can be sold. Except if the will didn’t grant the executor the authority to sell the property, the whole process could require the court’s approval, and that means scheduling (and then waiting, and then having) another hearing, just to be allowed to accomplish these tasks. And then someone has to be willing to purchase the property! Oy! (Where’s that aspirin?)
- Tax preparation and filings — Depending on the size of the estate, a federal estate tax return using Form 706 (including schedules A through W!) might be due 9 months after the person dies. And if the estate, itself, earned any income during that period (like from investment dividends, rental income, or a business), then the estate may have to file a federal income tax return. Plus, some states have their own estate tax and inheritance tax, so preparing returns and waiting for government entities to process them can takes several months depending on how complex the tax situation is.
- Contested wills — You’ve seen the ripped-from-the-headline cable movies. You’ve heard the gossipy stories. Everything seems like it’s going along smoothly and then someone objects to the will. It can be a creditor, an heir, or mysterious “other” and they might challenge whether the will is valid at all. Siblings argue that Grandma had no mental capacity to make the will or that another individual used “undue influence” to get a will revised. Sometimes, someone argues that an old will is real and a newly-found one is not (or vice versa). It can takes years for contested wills to complete probate!
Where you live can also determine how quickly the probate process goes. In the United States, probate takes an average of 9-24 months; if the deceased had no will, the process generally takes 2-4 extra months, although it can be longer. In Florida and Texas, probate may be completed in six months to a year; in New York and California, 1-2 years is more common.
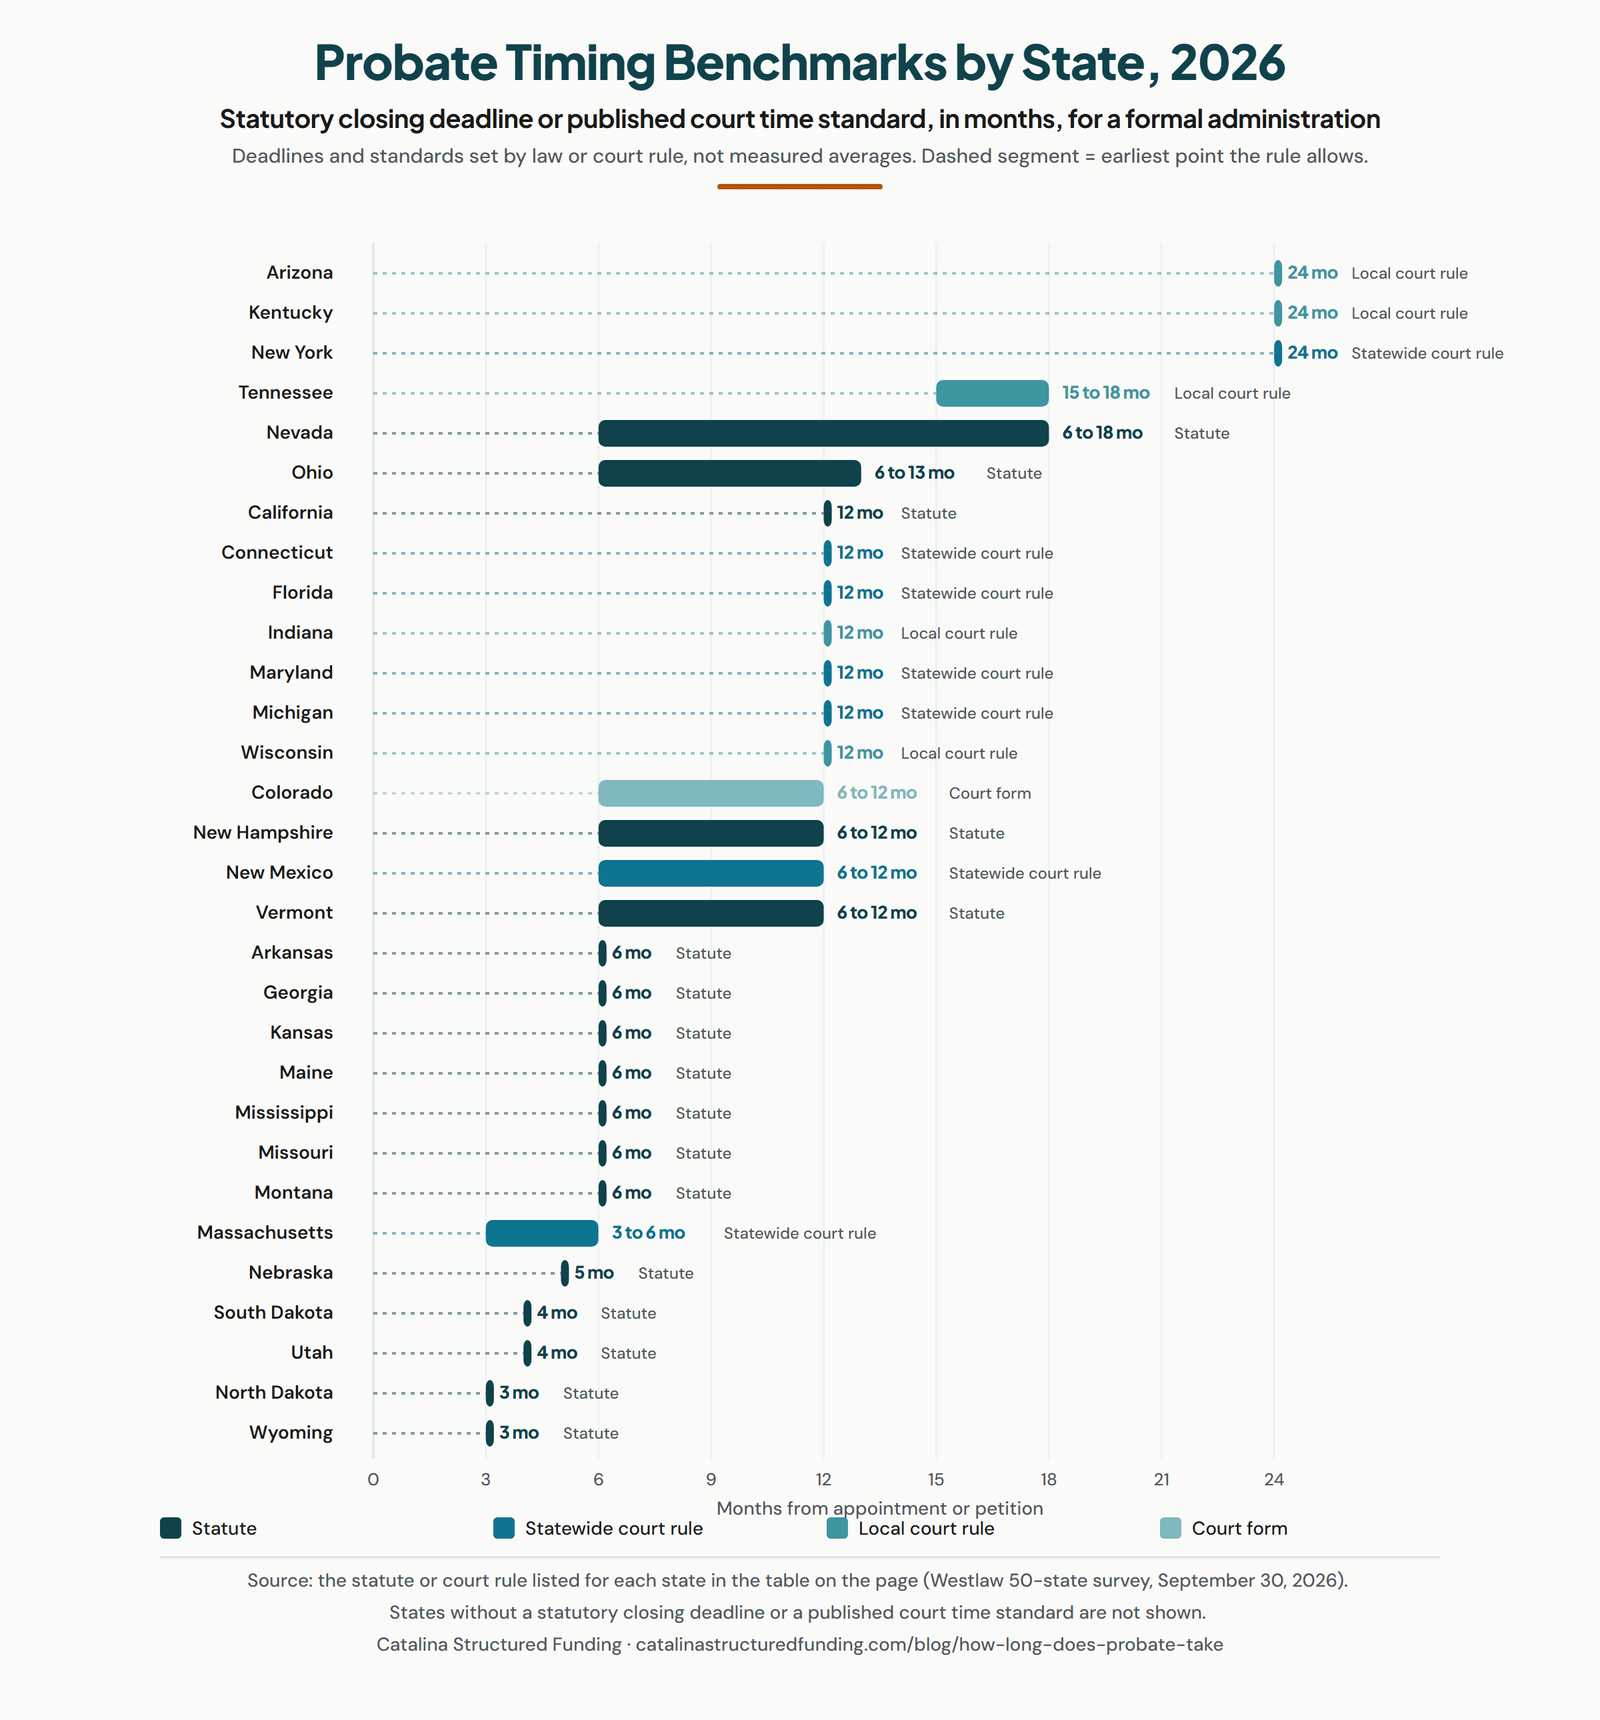
Chart: Catalina Structured Funding, “How Long Does Probate Take? State-by-State Timelines for 2026,” https://www.catalinastructuredfunding.com/blog/how-long-does-probate-take
The longer probate takes, the longer the delay before assets can be distributed to beneficiaries. Doesn’t it make sense to avoid or at least minimize the probate process?
Ensure Family Privacy
Did you know that probate proceedings are a matter of public record?
That means anyone, from your ex-mother-in-law to Gladys Kravitz can access the details of your estate holdings and know who the recipients of assets are. Maybe you’d rather the world didn’t know that Cousin Floyd left you stock in Playboy Enterprises. When you avoid probate, you get to maintain your family’s privacy.
Reduce Stress
Grief is difficult and unwieldy. When families are in mourning, loved ones feel surges of grief at unexpected times; it’s why you feel “waves” of grief, and why it’s important to keep from being pulled under.
Why add to the emotional pain of loss with a complex and lengthy probate period when you can make inheriting many of the assets easy?
Next time, we’ll explore the specific ways you can avoid probate, or at least limit the process, labor, and costs.
In general, there are three main categories of ways to avoid probate:
- Own property jointly
- Create (and then fill and fund) revokable living trusts
- Arrange for beneficiaries (through Payable-on-Death/Transfer-on-Death assignments)
That last bullet may seem like something you only do with life insurance or retirement accounts, but there are easy, no- and low-cost ways to transfer ownership of everything from bank accounts to stock holdings, and even cars and houses, and we’ll walk through them all.
As we go through this series, we’ll also look at how to organize information about your assets to make the probate process (or avoiding the probate process) so much easier for you and your loved ones.
Show Me the Money — A 2025 Guide to Finding Forgotten Funds & Unclaimed Property

Whether you spend a small fortune over each Black Friday/Cyber Monday weekend or you’re super-cautious with your dollars and cents throughout the year, I bet you’d like to have more money. And I bet you’d particularly like to have more of your own money — money that has been kept from you for some reason — back in your own pocket.
MISSING MONEY AND UNCLAIMED PROPERTY, REDUX
One of my most popular posts is one I published almost three years ago: Lost & Found: Recover Unclaimed Money, Property, and Savings Bonds. In it, I explained the basics of unclaimed property. To borrow from myself:
The term unclaimed property is what you’ll hear most often when searching for lost money in various types of accounts. Unclaimed property usually refers to funds that a government (federal, state, or local) or business owes you because you’ve, quite literally, left it unclaimed.
It’s possible that you’re so organized with your paperwork that you feel affronted that I’ve implied you might have just haphazardly left money sitting around. But I’m not saying you’re absent-mindedly leaving piles of cash wrapped in newspapers like Uncle Billy in It’s a Wonderful Life. (By the way, that $8000 deposit that ended up in Mr. Potter’s hands would be worth
$121,762 in 2023$132,913.23 in 2025! Maybe Uncle Billy should have tied the money to one of those strings around his fingers.)
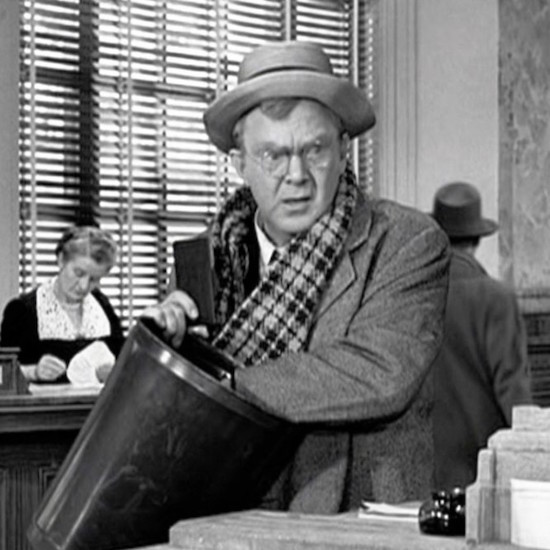
Thomas Mitchell as Uncle Billy, searching the bank’s trash cans for the lost Savings & Loan deposit. Let’s boo Mr. Potter!
I posited the various reasons why money gets separated from its rightful owner.
Sometimes, you’re due a refund, but the refund sits so long that a company loses track of you. Several years ago, when I began working with a client, I had sorted through all of his bills and paperwork to figure out what we could discard, what should be filed, and what required action. Typically, that last category involves paying a bill, but in his case, we found that he was owed money. He and his late wife had opened a retail store credit card to purchase a service they’d later canceled. A prorated amount was returned to the credit card, but because they never used the card again, the balance just sat there, neither accruing interest nor being used, statement after statement.
Happily, in this case, one call to the credit card company (and many, many transfers between departments) later, and within a week, he had a check for the amount. Better yet, that credit card company doesn’t send statements in months when there’s no (positive or negative) balance, so it also meant that he had less paper clutter!
Other times, you and your money are parted because you’ve done a magic trick and disappeared. Think of times when you’ve put down money, such as a security deposit for an apartment or a local utility account. The landlord or company holds your money as security, or collateral, in case you skip out on your payments. In many cases, that money is held in an interest-bearing account.
In the best case scenario, when you terminate your lease and cancel your utilities, you get back your deposit plus a little bonus (of interest) for your troubles. The problem is that too often (and particularly when we are younger), we’re so focused on where we’re headed that we miss out on what we are owed. However, if you left no forwarding address (and remember, in the olden days, when we moved, our phone numbers did not move with us), landlords and utility companies had no way to reach out and return that money.
In theory, that money is/should always be turned it over to the state.
These are only the most common examples of money that may have been left behind when you jetted off to the next part of your life. And, of course, most of us know the frustration of someone else not being clear about what or where valuable funds may be.
There are a variety of situations where your money might go unclaimed. Consider this a mental checklist to jog your memory of money that may have disappeared or been forgotten.
Financial Accounts
- Abandoned bank accounts
- Abandoned credit union accounts
It’s not uncommon to calculate how many outstanding payments will need to clear and leave only a bit more than that amount in a bank or credit union account you plan to close. The payments clear, and then the forgotten accounts often lay dormant, occasionally collecting interest.
Most bank and credit union accounts require some sort of activity — even just the deposit of $1, once per year — to be considered active. Banks won’t put in too terribly much effort before turning money over to the state.
Employment-Related Funds
It’s one thing to quit a job and leave behind forgotten leftovers in the break room fridge, but so many people manage to ghost their own money.
- Un-cashed checks or failed direct deposits — I’ve had clients who had been so overwhelmed and overworked that when they switched jobs, they forgot to cash their final paychecks. (Yes, even though most people are regularly paid via direct deposit, final checks are often issue with old-fashioned paper checks.)
I have also seen people fail to notice or remember — in the chaos of moving — that a final check was never actually direct-deposited; or perhaps that payment was issued, but the direct deposit failed to go through because the old bank account was already closed. I’ve seen all of these! And other payments may go un-deposited. Un-cashed checks might include:
-
- paychecks
- employment bonuses
- refunds of expenses submitted to your employer
- sales commissions
- vendor checks
Poor Milton. They kept moving his desk, and the Payroll Department could never find him.
Investment Instruments
It’s common for people to have chaotic investments. I try to get clients to list all of their accounts, but often have to play detective.
When you’re fresh out of college, you may have a few savings bonds (far from their maturity dates) and nothing else to speak of. However, after a variety of jobs (particularly if you started working before the era of 401(k)s and Roth IRAs), you may have picked up (and then failed to roll over) a smattering of retirement accounts.
If you came into adulthood before mutual funds were really a thing, your investment portfolio may include a random collection of individual stocks, some of which are in DRIPs (dividend re-investment plans) and others where you randomly get checks for $1.53 or $4.52…which you try to remember to deposit and then find smushed in the pocket of your winter coat on the first cold day of the season.
Consider the following investment instruments you may have forgotten that you even had after a lifetime of cross-country moves:
- 401(k)s
- Stocks
- Mutual fund holdings
- Bonds
- Other securities that were never transferred or claimed
- Dividend checks
- Fractional share cash-out checks
- Savings bonds — If you’ve lost your savings bonds, be sure to read the latter part of Lost & Found: Recover Unclaimed Money, Property, and Savings Bonds.
- Israeli bonds — Note, if you do not have your original paper bonds, be prepared to jump through some hoops!
People change addresses, firms merge or dissolve and then change names, stocks split or get sold off — whether they lost track of you or you lost track of them, it’s all worth tracking down.
Insurance Policies
Have you ever seen Gerber Life Insurance — yes, like the Gerber baby food. It’s whole life insurance advertised to parents to give their children life-long guaranteed coverage. Debating the pros and cons of getting life insurance for children is beyond the scope of this post; however, paying attention to organizing the documentation/paperwork for such policies is key.
After having been a professional organizer now for almost a quarter of a century, I have worked with many clients who, when they clear out their elderly parents’ homes, find random references or partial documents for those kinds of baby life insurance policies. In every case, the cash value of those policies have long-since stopped increasing in value.
Sometimes, they’ve been able to cash out directly but often the policies have been sold and resold to other insurers who have lost track of the policy-holders and turned the money over to the applicable state governments. (Are you noticing a trend? Even companies with everything organized by 21st-century computers don’t want to keep up with the nickels and dimes of seemingly abandoned accounts.)
Insurance-related money may be owed to you in the form of:
- Matured insurance policies
- Terminated insurance policies
- Life insurance payouts
- Annuities
- Unclaimed insurance refunds — If the beneficiaries of insurance policies fail to claim death benefits, or policy-holders never cash refund checks (either because they never receive them or because they pile the mail on top of the microwave and it gets lost), that money goes unclaimed.
Legal Balances
If you won a million-dollar judgment, Paper Doll suspects you’d probably notice if you forgot to accept payment, but there are a variety of funds (usually far less than seven figures) that are legally yours but may be forgotten. When you go spelunking for unclaimed property, you may find you are due money for:
- Trust distributions
- Inheritance-related funds — This is a good reminder that your heirs can’t claim assets that they don’t know exist, so make sure you provide detailed records for your loved ones. For more on that, check out two classic Paper Doll posts: Reference Files Master Class (Part 2) — Financial and Legal Papers and How to Create, Organize, and Safeguard 5 Essential Legal and Estate Documents
- Unclaimed court deposits
- Escrow funds from real estate deals
- Proceeds from legal settlements or judgments — These may include class-action payouts, money returned to you for bond or bail, garnished wages meant to cover unpaid child support payments.
A client’s ex-husband once owed her a significant amount of back child support; she couldn’t collect because when the ex had arranged to be paid “under the table” so as not to have his wages garnished. However, when he won a significant judgment in an unrelated lawsuit, my client was able to receive what was due to her and her children because she had made the effort to keep the state agency overseeing child support enforcement updated whenever she moved.
- Royalties owed for minerals, oil, gas, or other assets you own. (Your Grandma once owned land in Oklahoma or Texas? Think Dallas, but with more paperwork and fewer shoulder pads.)
- Royalties owed for creative works, like published books or music, recorded performances, etc.
Have you ever heard of Sixto “Sugar Man” Rodriguez? He was a Mexican-American musician in the late 1960s and 1970s, whose songs focused on the societal difficulties facing those living in poverty. When his albums sold poorly in the United States, he ended his music career. Unbeknownst to Rodriquez, his music was so popular and influential in South Africa that it was said he sold more records there than Elvis Presley. But for decades, he wasn’t aware of, or paid royalties for, his talents — as told in 2012’s Oscar-winning documentary Searching for Sugar Man, fans even mistakenly thought he was no longer alive!
If you’re due royalties make sure you are findable!
FIND GENERAL UNCLAIMED PROPERTY OR FUNDS
As I explained in the original post three years ago, there’s not one central database for all unclaimed property. Generally, unless the money you’re seeking is in a special category (see further below), you should start your search in the unclaimed property office for each state in which you have lived.
Begin with Unclaimed.org, the website of the National Association of Unclaimed Property Administrators. (For detailed instructions for your search, see my original post.)
To search for multiple states simultaneously head directly to MissingMoney.com.
MissingMoney.com allows you to just type a first and last name, and all possibilities for that name, across all state databases, will come up.
FIND MISSING RETIREMENT AND EMPLOYMENT BENEFITS
Do you vaguely recall having some funds trickling into a pension or 401(k), but you’ve had several jobs, homes, and kids since then? Is it all fuzzy?
If you’ve kept meticulous records, you may have files about your old retirement accounts; if you’ve kept mediocre records, you may have an old address book with the names of former colleagues whom you could find on Facebook or LinkedIn, and ask if they remember what retirement benefits you were supposed to have. However, there are more official methods for tracking down your hard-earned benefits.
Retirement Savings Lost and Found Database
Did you know that the US Department of Labor’s Retirement Savings Lost and Found Database can help you find your lost or missing retirement funds? Run by the Employee Benefits Security Administration (EBSA), the database should be your first stop if you or a loved one has lost track of an old pension or 401(k). Per the website:
EBSA is helping America’s workers and beneficiaries search for retirement plans that may still owe them benefits by establishing a public Retirement Savings Lost and Found Database through the SECURE 2.0 Act of 2022.
This database serves as a centralized location to find lost or forgotten benefits and get information on how to obtain those funds. Learn about the tools and resources available for you to recover your hard-earned benefits.
Visit lostandfound.dol.gov — but note that to access the database, you’ll need a valid ID-Proofed Login.gov account, first.
Once in, you’ll be able to search for any retirement plans that were a) linked to your Social Security number and b) sponsored by private-sector employers and unions. The database includes:
- Defined-benefit pension plans — any kind of benefit plan that guarantees either a lump-sum payment when you retire or a lifetime monthly payment, like an annuity
- Defined-contribution plans — accounts that employees fund during the years that they work, such as 401(k)s, and which continue to grow while they work and after they retire.
The Retirement Savings Lost and Found Database doesn’t include Social Security benefits, personal investments like individual retirement accounts (IRAs) or retirement plans sponsored or overseen by religious organizations or government entities. So, if you’re a senator or a nun (or, y’know, a court clerk or church secretary), this database isn’t for you.
Pension Benefit Guaranty Corporation

Have you ever worked for a private-sector company or organization whose retirement plan went kaput?
The Pension Benefit Guaranty Corporation (PBGC) Database, is responsible for holding any unclaimed benefits for current or employees where the retirement plan ended and not everyone got their payout.
Search the database to find your benefit plan; just enter your name and the last four digits of your Social Security number. Once you verify that PBGC is holding your benefits, follow the instructions for submitting documentation to claim them. (Once again, a plug for getting your Very Important Papers organized).
Other Retirement Benefits Solutions

The National Registry of Unclaimed Retirement Benefits (NRURB) operates a free database to assist former employees, employers, and plan managers to find one another and ease the problem of distributing retirement benefits that have been forgotten (by the accountholder) or abandoned (by the plan administrator). They use Department of Labor data and information from employers to help identify lost and/or unpaid benefits.
Speaking of abandoned plans, the Department of Labor’s EBSA also operates an Abandoned Plan Search database to help you find a plan abandoned by its administrator. (Maybe those administrators need to hire some professional organizers?)
If you’re still having trouble securing your company-sponsored retirement benefits, you may want to contact the non-profit Pension Rights Center. They operate the U.S. Administration for Community Living’s Pension Counseling and Information Program, and if your company or pension plan operates in one of the thirty states they serve, you may be able to access their free legal services.
Find Unpaid Wages through WOW
Did you know that if an employer breaks labor laws, the Department of Labor’s Workers Owed Wages program is empowered to try to recover your back wages?
If you think you may be owed back wages from your employer, search the WoW database. Don’t dilly-dally, though, as they only hold unpaid back wages for three years.
Find the database at https://www.dol.gov/agencies/whd/wow.
FIND UNCLAIMED LIFE INSURANCE POLICIES
Unclaimed insurance payments are typically turned over to the state. However, there are some situations where money may be owed related to federal insurance policies.
- VA Life Insurance Unclaimed Funds — The U.S. Department of Veterans Affairs (VA) has a database for searching unclaimed insurance funds. The VA holds onto money it owes to current or former policy holders or beneficiaries of those policies whom they’ve been unable to locate.
When my father, a WWII veteran, died in 2018, I had access to the paperwork related to a life insurance policy he was given upon leaving the Army at the end of the war. Contrary to expectations when dealing with government agencies, I was able to resolve all of my questions with one call. However, had I not had access to any of the paperwork, the link above would have been my first stop.
Note: the database doesn’t include funds from Servicemembers’ Group Life Insurance (SGLI) or Veterans’ Group Life Insurance (VGLI) policies from 1965 to the present day.
- FHA-Insurance Refunds – Homeowners who previously had an FHA-insured mortgage may be eligible for refunds issued by the U.S. Department of Housing and Urban Development (HUD).
Click on the link above to access the HUD database. Scroll down and provide your name, FHA case number, city, and state.
FIND UNCLAIMED MONEY FROM BANKING & INVESTMENTS
Did your bank fail? What about your credit union? Were you scammed by someone like Bernie Madoff?
- If you had money in an FDIC-insured bank that failed, you can search for your unclaimed funds at https://closedbanks.fdic.gov/funds/.
- If your money was in a failed credit union liquidated by the National Credit Union Administration, the NCUA.gov site’s Unclaimed Deposits database can connect you to your funds.
- Were you an investor parted from your money as a result of a bad-faith investment manager? The Securities and Exchange Commission (SEC) lists “enforcement cases” where individuals or companies money to their investors. You can check the status of distributions to harmed investors at SEC Claims Funds.
THINK OUTSIDE THE MONEY BOX
All of the categories described above cover unclaimed funds that someone else is holding. However, you may have money, or something just as good as money, hiding in your drawers and glove compartments and under the piles of papers on your desk:
- Unused loyalty points, rewards, and frequent flyer miles — These represent quasi-lost money, things with value but only if you use them. Bear in mind that some unredeemed points, rewards, and miles have expiration dates or may be considered abandoned if you don’t use them (or the apps/accounts) for a long while.
- Unredeemed gift certificates, store credits, refunds, or vouchers from retailers service-based companies. Depending on the state in which you live, they may be treated as unclaimed property if they go unused too long. Remember that year Aunt Gertrude told you that she schlepped out in a snow storm to get you that gift card for for Bed, Bath, and Beyond, and a Toys ‘R Us gift card for your tiny human? Uh-oh. Too late now. Stores close or restructure, and value goes poof!
- Contents of safe-deposit boxes — When people move or pass away, families may forget about the contents of old safe deposit boxes, and it’s very hard to reunite tangible property with original owners or beneficiaries.
In short: unclaimed property is often “anything owed to you that you forgot existed.” Take time to search for whatever may be owed to you or loved ones who can no longer search for themselves.
Remember, unclaimed property comes in many forms, from many possible sources.
As always, when you keep good (and organized) records (with account numbers and names of institutions, and your own addresses over the years), the search and claim processes will be easier. When searching databases, consider that your identity (or that of a deceased loved one) may not have been quite so organized — check name variations: with and without maiden names, nicknames, initials vs. middle names, etc.)
Good luck finding unexpected funds!
Paper Doll’s Ultimate Guide to Organizing Yourself to Get a REAL ID
On Friday, I renewed my driver’s license. Typically, that wouldn’t be blog-worthy.
I’ve lived in Tennessee for more than three decades, and generally I’ve been able to renew my license at a little kiosk that looks like an ATM. I’d verify some information on a screen, get a new (horrible) photo taken, and pay with my debit card, all in the vestibule of the DMV while avoiding the packed waiting area.
Not this time, though. I wasn’t merely renewing my license; I made an appointment to apply for my REAL ID, and had to engage with the DMV representative behind the glass barricades.
WHAT IS A REAL ID?
In 2005 (and yes, that really was twenty years ago), Congress passed the REAL ID Act in the long shadow of 9/11-related security concerns. The Act did the following:
- Set clearer standards for government-issued photo IDs — So, if you have a driver’s license, your great-grandmother has a non-driver ID card, or someone you know has different government-issued ID card, they will all fall under an established and uniform set of security standards so everyone will be on the same page.
- Prohibited various government agencies (including the TSA) from accepting forms of identification that don’t meet the new standards. For quite some time, TSA agents had some wiggle room in letting people on airplanes even when/if they didn’t have proper identification (such as when they lost their wallet or had their ID stolen, and showed up at the airport desperate to make a flight). No more.
- Added an extra layer of security to the process of flying — Having uniform requirements for flying makes it much harder for someone to use false documents to board an airplane or gain access to secure facilities.
Basically, the REAL ID Act established minimum security standards for state-issued driver’s licenses, permits, and ID cards to reduce identity fraud.
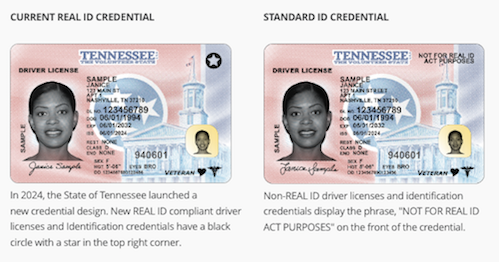
REAL ID: A LONG TIME COMING
Dear Paper Doll Readers, you know I always try to share information with you in good faith, but ever since I originally blogged about the REAL ID, the US Department of Homeland Security has turned me into the boy who cried wolf.
Originally, the federal government wanted the new regulations to go into effect in 2008, but many states and territories opposed to the immense effort it would take to comply.
First, not all states had required photos for driver’s licenses; conversely, REAL IDs require facial image capture and states need “an effective procedure to confirm or verify a renewing applicant’s information.” To anyone who has watched too many episodes of Law & Order and other police procedurals, it’s a bit surprising that not every state was verifying that faces and names matched!
Second, states would have to confirm Social Security account numbers with the Social Security Administration and cross-check to make sure old or expired licenses were “terminated” in other state’s systems before taking effect in the state where someone was applying.
Third, states were going to be required organize and maintain the documentary evidence submitted. For example, each state would be need to either retain paper copies of documents for a minimum of 7 years or scanned/capture images of those source documents for a minimum of 10 years.
Fourth, states must limit the validity of all driver’s licenses and (non-temporary) ID cards to 8 years; some states had previously kept IDs valid for ten years.
Lacking professional organizers to keep their processes straight, state governments were not particularly keen on having make these changes! Kerfuffles ensued. From 2012 through 2018, states and territories acted in fits and starts.
Eventually, the federal government announced that it would require REAL IDs effective October 1, 2020. However, as we all know, 2020 didn’t exactly turn out as anyone planned, and the CARES Act (remember that $2.2 trillion COVID stimulus package?) delayed the start to September 30, 2021. Later, after several more changes to documentation and funding regulations, the date was pushed to May 3, 2023.
And now, finally, the official date appears to be on the horizon: May 7, 2025, which is (as of this writing), 57 days away!
If you already have a REAL ID-compliant license or other identification, you’re good, but if your license wasn’t due to renew over the past five years or so, you might have figured there was no need to rush to upgrade. But now, it’s time to pay attention.
WHY MIGHT YOU NEED A REAL ID?
Now that you understand why the government has been working toward this change for the last twenty years, you may wonder how it affects you. Why might you need a REAL ID?
1) You Need a REAL ID to Fly
As of May 7, 2025, in order to board an commercial aircraft, your identification must be REAL ID-compliant. Some people seem to believe that flying for particular purposes makes the new law inapplicable to them, but just to be clear, the REAL ID Act will apply no matter what kind of commercial flying you will be doing, including:
- business travel
- vacation/pleasure travel
- heading to college (or taking your children to/from college)
- accompanying minor children during a custody transferral
- traveling to care for ill relatives
- getting health care from specialists in distant cities
- looking for houses in a city to which you’re moving
United Airlines Red Carpet, courtesy of 1950sUnlimited, CC BY-NC 2.0
Do you need a REAL ID to fly on a private plane?
Yes!
Even if your non-commercial flight has private screening or you travel through a private FBO (fixed-base operator), the REAL ID act still sets — and the TSA must enforce — a minimum security standard for all air travel.
Do you need a REAL ID to fly on Air Force One?
No, but that’s because it’s categorized as a military (not commercial) aircraft used for official government travel. Journalists and politicians authorized to fly on Air Force One go through such thorough vetting by the Secret Service that gathering documents to secure a REAL ID will seem like a walk in the park.
Do you need a REAL ID to fly a crop duster?
Nope.
A crop duster is an agricultural aircraft, so flying in one is not considered commercial airline travel and therefore doesn’t fall under the REAL ID requirements. However, to work as an agricultural pilot, you must earn a private pilot license, a commercial rating, and a tail-wheel (conventional gear) airplane endorsement, and get specific agricultural aviation training. That seems like a lot of extra effort to just to avoid going to the DMV to get your REAL ID.
Do you need a REAL ID to fly firefighting aircraft (like air support to drop water or fire suppression chemicals on a fire)?
Sometimes, actually, yes. These aircraft, like those operated by Cal Fire during the recent fires, are sometimes considered commercial aircraft. I was surprised, too.
If you’re not familiar with these aircraft that drop water or pink suppression chemicals, may I point you to the CBS TV show Fire Country, or if you’re feeling up for something sappy but wonderful, the star-studded aerial firefighting movie Always, a remake of a WWII-era film A Guy Named Joe.
Do you need a REAL ID to fly on a rocket like SpaceX, Virgin Galactic, or Blue Origin?
Yes! These non-NASA rockets are considered commercial flights. Pack your REAL ID.
But no, you don’t need a REAL ID to go hot air ballooning like Dorothy in The Wizard of Oz, as there are no TSA checkpoints in the sky!
Can’t you just use a passport to fly? What about a Trusted Traveler card?
What a smartypants you are! In order to fly, you must have a REAL ID-compliant document, which includes a US passport or passport card (the acquisition of which already requires the kind of documentation required for a REAL ID).
However, most Americans do not have valid passports. Currently, only ~45% of Americans hold one. If you have a passport, you’re set; if not, and you aren’t likely to do international travel, a state-issues REAL ID is a more economical choice.
Trusted Traveler program cards, like Global Entry, TSA Pre-Check, NEXUS, SENTRI, and FAST are REAL ID-compliant, but are pricier than a driver’s license and may not be applicable to your lifestyle.
What about a state-issued Enhanced Driver’s License?
Michigan, Minnesota, New York, Vermont, and Washington issue these for land or sea border crossings with Canada, Mexico, and the Caribbean. They require the same documentation and count as REAL ID-compliant; if you have one, you already know it. But if you don’t, and unless you live in these states and don’t have a passport, go ahead and upgrade your driver’s license.
2) You Need a Real ID to Enter Secure Federal Buildings
If you have reason to enter any secure federal buildings, you’ll need REAL ID-compliant documentation.
Panorama of United States Supreme Court Building at Dusk courtesy of Joe Ravi, CC BY-SA 3.0
You may be thinking, “When the heck will I ever have to go into a secure federal building? I’m not a judge or legislator!” However, you might go to a federal building to:
- apply for or renew certain federal benefits — For example, some Social Security Administration offices are in federal buildings.
- access services at a VA facility — While most VA medical centers won’t require REAL ID, some administrative offices do.
- attend an immigration or visa appointment
- work in or visit a federal agency — If you’re a contractor or consultant, or if you’re applying for a federal job, or if you need to visit the IRS, EPA, or Department of Labor, know that such offices are in federal buildings
- attend a public hearing or town hall — Agencies hold open meetings for the public on policy matters.
- attend a government conference or training — Federal agencies host public events, seminars, and professional development sessions.
- retrieve records or conduct research — Agencies like the National Archives or Library of Congress require in-person access to certain records.
- serve on a federal jury or grand jury
- give testimony in legal proceedings — And no, if you’re accused of a crime at the federal level, you can’t get out of being tried for that crime just because you don’t have a REAL ID.
- report to a federal probation or parole office
- visit an inmate in a federal detention center
The REAL ID Act doesn’t require you to present identification anywhere it’s not currently required for accessing a federal facility.
So, while all federal buildings have security, they don’t all count as “secure federal facilities.”
You don’t need a REAL ID to visit the National Archives museum or its reading rooms, but you do need a valid form of identification to enter the research rooms. Similarly, you don’t need a REAL ID to visit the public areas of the Smithsonian Institute.
3) You Need a REAL ID to Enter Nuclear Power Plants
Do you work in a nuclear power plant?
Are you a government employee whose job it is to inspect nuclear power plants? Engineers, safety inspectors and maintenance crews often have to visit plants for inspections and upgrades.
Are you a government regulator from the Nuclear Regulatory Commission or the Environmental Protection Agency?
Are you a vendor or contractor for a nuclear power plant? Whether you restock the candy machines or service the bathroom plumbing or do public speaking events for the staff, you’ll need a REAL ID-compliant document to gain access.
Are you a first responder? Emergency personnel, firefighters, and HAZMAT teams often train in nuclear facilities.
Are you an energy industry professional or a policymaker taking a tour? Are you a journalist? A researcher? You’ll need that REAL ID!
Are you a teacher or professor planning on taking your students to visit a nuclear power plant? If you’re taking third graders on a tour of a nuclear power plant — wow, that’s weird — they wouldn’t need to be REAL ID-compliant, but if you’re a college professor, your age 18+ students would.
Are you Homer Simpson?
One assumes this also applies to Mr. C. Montgomery Burns (Homer’s boss) and sycophantic Smithers. However, Mr. Burns is a billionaire, and they seem be getting a lot of special treatment lately. Your mileage may vary.
WHEN DON’T YOU NEED A REAL ID?
- If you’re a kid — Children under 18 are not required to have REAL ID-compliant identification.
However, I strongly encourage you to make sure your college-bound students get their IDs as soon as they are able, particularly if they attend school more than a few hours’ drive away. From Spring Break to getting home for a family emergency or a funeral, help them be prepared.
- If you’re showing ID to vote — You can’t be required to show a REAL ID to vote.
The REAL ID Act is for maintaining security, so as long as your assigned polling place is not on an airplane, in a secure federal building, or in a nuclear power plant, you should not be required to have or show a REAL ID-compliant identification. (For more on IDs for voting, see my post, The Ultimate Guide to Organizing Yourself to Vote.)
What if you aren’t a US citizen?
If you’re a tourist, you’ll have a passport, which serves the same purpose. If you are neither a citizen nor tourist but are lawfully present in the United States, you can obtain a REAL ID, provided you can demonstrate your legal presence and meet other requirements.
Remember, this doesn’t just include citizens of the 50 states and Washington, DC. If you live in Guam, Puerto Rico, American Samoa, the US Virgin Islands or the Northern Mariana Islands, the REAL ID Act applies to you, too.
REAL ID MINIMUM DOCUMENT REQUIREMENTS
To be a valid REAL ID-compliant state-issued ID (whether a driver’s license or other identification card), it must include the following:
- Full legal name
- Date of birth
- Gender*
- Driver’s license or identification card number
- A digital photograph
- Address of principle residence
- Signature
- Physical security features designed to prevent tampering, counterfeiting, or duplication of the document for fraudulent purposes.
- A common machine-readable technology, with defined minimum data elements.
*Until recently, the gender marker on a passport could be M, F, or X. However, the current administration has announced that the X marker will no longer be allowed on renewed/new passports issued and the marker must match the individual’s assigned sex at birth. However, at least right now, states can make their own rulings regarding gender markers on REAL IDs.
Remember, REAL ID is a set of standards, not a national identification card. Each state issues its own unique licenses and ID cards.
SO, HOW DO YOU GET A REAL ID?
First, gather your documents. You will need to present the following types of original or certified documents to your state to apply for a REAL ID.
- Proof to establish citizenship or legal presence — Again, if you have a passport or passport card, you’re covered. Otherwise, you’ll need official documentation, like:
- a birth certificate
- US Certificate or Consular Report of Birth Abroad
- a valid, unexpired Permanent Resident card issued by DHS or INS
- a certificate of citizenship or naturalization
- an unexpired employment authorization document issued by DHS
- an unexpired foreign passport with a valid US visa and approved I-94 form
- Proof of your full Social Security number — Find your official Social Security card. If you’ve lost yours, replace your Social Security card as I explained in How to Replace and Organize 7 Essential Government Documents before applying for a REAL ID. However, my state gave me the option of alternatively showing a W-2, 1099, or payroll check stub bearing my SSN.
- Two proofs of residency of the state in which you currently reside — My state offered more than a dozen options, including a recent home utility bill, a vehicle registration, a voter registration card, an IRS tax return, a bank statement, and a variety of other financial and insurance documents.
- Documentation of any name changes — due to marriage, divorce, adoption, change of name (associated with a gender reassignment or otherwise, etc.), explaining a discrepancy between the names on all your forms of proof.
Safeguard your documents; don’t just put them in a manilla folder where they can fall out or damaged by inclement weather. I used a teal Container Store vinyl zippered document pouch because it looked like it might rain.
Next, make an appointment to apply at a local branch of your state’s Department of Motor Vehicles or equivalent. You must apply in-person, and it’s possible that only some (or even one) DMV location in your community will process these applications. Don’t just show up when you have a free afternoon, unless your idea of fun is rubbing elbows with random strangers in uncomfortable plastic seats.
Make yourself look presentable. You’ll be showing this ID all the time. (Also note: you’ll be required to take off your glasses for the photo, so try not to squint.)
Give yourself ample time to arrive. (I was told to arrive 15-minutes before my appointment. I got stuck behind a train and was only 10 minutes early.)
Be prepared to check in on your phone using a QR code. Many people were befuddled by this process and it delayed their appointments.
Be kind; the DMV staff goes through a lot. The wonderful representative processing my application spilled some serious tea about the way some people behave. (People apparently show up for their appointments while on drugs. People get high and then suddenly feel the need to renew their licenses? Seriously?)
HOW DO I KNOW IF MY ID IS A REAL ID?
Look in the upper right-hand corner of your ID. Do you see a star that looks like any displayed below?
No star? It’s not REAL ID-complaint. (In addition to the star, Enhanced Driver’s Licenses will have an image of the United States flag and the word “Enhanced” at the top of the card.)
For further information, check the Department of Homeland Security‘s REAL ID Frequently Asked Questions page.
Because my papers are organized, it took me about five minutes to gather my documents, and another five to make the appointment online. Even delayed by the train, I arrived ahead of my 2 p.m. appointment.
When my number was called a few minutes later, I was walked through the process of providing all of my documents, signing required statements, and getting my photo taken. At one point, all of the women behind the counter and several applicants stopped to call attention to a very handsome man with a dazzling smile (who looked quite a bit like the actor Donald Glover) getting his ID photo taken.
Dani Pudi, Betty White, and Donald Glover Doing the Anthropology Rap
I was back in my car at 2:21 p.m. It had taken longer to fix my hair for a good DMV photo than to apply for my REAL ID.
Getting organized makes obtaining a REAL ID REAL(ly) painless.
Follow Me