Paper Doll
Who Knows Your Secrets? Part 6: Many Happy Returns (and a Recap)
In lieu of sugar plums, many of you have visions of turkey and stuffing and cranberry sauce dancing in your heads. For other readers, Thanksgiving is about far-flung family members coming together to play a Kennedy-esque game of touch football on the front lawn (or, more likely, mom doing a semester’s worth of her college freshman’s laundry).
But for one subset of readers, this Thanksgiving week is the culmination of 51 weeks of intensive training. For such intrepid souls, Thursday’s big meal merely provides sustenance for the grueling work of conquering doorbusters and early bird sales. For these people, it’s all about Black Friday!
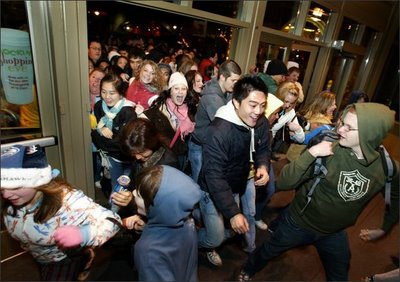
No professional organizer worth her salt (and Paper Doll considers herself sufficiently salty) would neglect, at this point, to illustrate the value of purchasing gifts of experiences (restaurant and movie gift certificates, theater tickets, zoo and museum memberships, etc.) and knowledge rather than tangible presents that will likely turn into must-dust, must-dryclean clutter within a matter of weeks. That said, for those insistent upon getting up early (or not sleeping at all), standing in freezing rain until the doors burst open (please, please be careful out there!) and shopping until you drop, there’s one last paper trail report you should know about: The Retail Equation!
If you like to pick up a pile of goodies and head straight for the cashier, figuring that you (and the kids, and your gift recipients) can try things on later and return them if they don’t fit (bodies or personalities), this is definitely a topic for you. You may have noticed recently that when you return or exchange an item, you’re likely to be asked to whip out your driver’s license. (No, you don’t have to prove you’re young enough to be seen in that mini-skirt in public or old enough to play Candyland.) It’s all part of a vast network to keep track of returns and exchanges in hopes of preventing fraud.
Retailers outsource their risk analysis (just like the insurance companies and lenders we’ve been discussing for weeks) to The Retail Equation (formerly The Return Exchange). This company maintains a database of consumer behavioral patterns, including frequency of returns or exchanges, the dollar amounts of what is being returned (or exchanged) and the elapsed time since the original purchase (and how that time frame compares with the store’s stated return/exchange policies).
Even if you’ve done nothing wrong, if you tend to make a lot of returns or exchanges, you may find that more and more retailers will be refusing to accept the returns. That’s a big “Yikes!” to shoppers who have a habit of bypassing the dressing rooms to make sure clothes fit, or who shop for their growing children without the kids in tow.
Retailers tend to disallow returns if they fall into one of two categories:
- Returns that break the retailer’s return policy, such as a return without a receipt, after the allowed return period or too many returns in any given period.
Depending on the state in which a retailer operates, it may or may not be required by law that the company post the policy, so it’s a good thing to look around the cashier area or back of your receipt to find a stated policy. If you don’t see a written policy, ask the cashier what the requirements are. Some stores require returns within 14, 30 or 60 days while others have no stated limits. Other stores limit the dollar value of items or number of purchases that can be returned in any given period (usually one business day). And most stores require a receipt with any return.
- Return behavior that could be construed to be abuse of retail policies
This category includes purchasing big ticket items and returning them immediately after a specific event, like buying a big screen TV the day before the Super Bowl and returning it the day after, or purchasing a prom dress and returning it in mid-June. In the retail industry, this is called renting or wardrobing…and Paper Doll would like to go on the record to say that it’s just really tacky.
The Retail Equation’s patented Verification-1 software system is designed to identify fraud and abuse related to returns, a $15.5 billion problem in the United States. The system is formulated to deter the less than 1% of shoppers (i.e., not you, dear readers) whose behaviors “mimic return fraud or abuse”. The biggest concern is merchandise that is stolen, then “returned” or exchanged, and indeed, some thieves will retrieve the receipt you throw in the trash, steal that exact item and then use your receipt to make a return.
In general, you shouldn’t have to worry as long as you follow some basic rules:
- Keep your receipts for items that you’ll have a likelihood of returning (and get gift receipts for presents to make it easier for your recipients to return a too-snug sweater or duplicate DVD).
- Note the return periods for the items you buy. Consider making a notation on your calendar for the Saturday prior to the close of a return period for the things you’ve made during a big shopping trip.
- Avoid those questionable return behaviors, like “renting” big ticket purchases for one-time events and then returning the gently-used items. (I’m sure no Paper Doll reader would even consider such behavior.)
Unlike all the other reports we’ve been discussing over the last month, The Retail Equation is not categorized as a credit reporting agency (CRA) according to the Fair Credit Reporting Act, so consumers do not have a legal right to annual copies of their reports or a dispute policy requiring speedy investigation.
However, if an identity thief has stolen your good name (and checkbook) and is buying up goodies and making returns for quick cash, you do have a means of regress. If you’ve had a return rejected (or are just concerned about the paper trail The Retail Equation has been keeping on you):
Send an email to returnactivityreport@theretailequation.com with your name and phone number.
A representative will return your call and ask you to provide some identifying information, including your driver’s license number and state, and the transaction ID from your attempted return. (If you didn’t make a return and are just checking your report, simply say so.)
It’s not a particularly speedy or automated process, but it does give you insight on your shopping and return habits. And, perhaps, if you’re returning so many purchases, it could mean that you don’t really need that kind of clutter in your life and that shopping isn’t the most fulfilling hobby for you. Just a thought.
Over the past month, we’ve been looking at all the data being collected about us as we go about our daily lives as consumers. Our credit reports, our banking habits, our homeowner and auto insurance claims, the medical tests we undergo and the prescriptions we fill–all of this information is collected by third parties and distributed to lending institutions and insurance providers, so they can determine whether we’re shiny pennies worthy of their trust or too risky for them to serve (or serve inexpensively).
The good news is that these reports, if accurate, can reflect the hard work and dedication we’ve put in to building solid personal paper trails of responsible spending and banking, safe driving, and good, clean living.
The bad news is that an identity thief, whether purloining our financial or medical identities, can wreak havoc on the information in these consumer reports. Almost as bad (if not as intentional), keystroke errors by data entry workers can link the financial histories of a Junior with a Senior or a John Q. Public with a Jon Q. Public, or exchange the information of two unrelated people with similar names or Social Security numbers differing by one digit.
All of this can cause us to pay double-digit interest rates for mortgages and credit cards, and increase our insurance rates (for homeowners and auto to health, life, disability and long-term care policies) beyond the reach of affordability. Unnoticed, such fraud or errors might even keep us from obtaining credit, bank accounts or insurance of which our true histories would deem us worthy.
The final good news (everything cycles around again) is that the Fair Credit Reporting Act ensures that for all of the reports we’ve discussed (with the exception of The Retail Equation), consumers have the right to free annual reports, free reports whenever an adverse action is taken against them (such as denial of service), the opportunity to dispute errors and have them investigated and corrected in a speedy manner, and the chance to have your side of events be included in your file if the reporting agency refuses to make the requested correction.
To recap our Who Knows Your Secrets series, we’ve covered:
From Little Sister to Big Brother (Your credit reports and who can access them)
Checking Up On Your Checking History (Safeguarding Your Bank Accounts)
Get A CLUE About Insurance Reports (Get the Insurance…and Rates…You Deserve)
Someone’s Snooping In Your Medicine Cabinet (Your Health History)
Employers & Landlords & Yentas: Oh, My (Everyone Else Who’s Up In Your Business)
While the topic of your consumer paper trail isn’t exactly turkeylicious, Thanksgiving is the unofficial start of a holiday season in which we need be ever more vigilant about our expenses and our financial lives. Please let this series of posts stand as mile markers as you traverse your paper trails…over the river and through the woods.
Readers, Paper Doll wishes you all a happy, healthy Thanksgiving.
Who Knows Your Secrets? Part 5: Employers & Landlords & Yentas: Oh, My!
Supreme Court justices and reality show contestants aren’t the only folks subject to background checks, and government and corporate vetting committees aren’t the only ones digging for dirt. Employers, dating services, landlords, wealthy parents of celebutantes–all have an interest in checking out somebody’s background.
EMPLOYERS
In our increasingly litigious society, many employers feel they must perform background checks to protect themselves against negligent hiring lawsuits. With an eye to prevent child abuse or abduction, the background of anyone who works in childcare or teaching will be investigated for past criminal activity. School and organizational athletic leagues must check out their volunteers and coaches to maximize the safety of the children–even the CDC has guidelines for screening such applicants.
Large corporations with major financial or corporate secrets feel the need to make sure there are no bits of grit on the squeaky clean reputations of their executives that might leave them open to blackmail or extortion. And of course, in light of modern terrorism of all sorts, background checks can bring to light histories of violence or other aspects that might make a particular person an inappropriate candidate.
Some of the reasons behind employer-driven background checks need not be as serious–sometimes they just want to make sure you are who and what you say you are. In promos for the new NBC series Community, attorney Joel McHale shares that he’s in trouble because of his undergraduate degree. “I thought you went to Columbia?” queries the friend. Joel replies, “And now I have to get a degree from America.” (Yes, the play on Columbia vs. Columbia doesn’t work as well in print.) Governments, universities, hospitals and corporations need to be sure that the lofty claims on applicant resumes are checked out in detail.
Sure, some employers are satisfied to call references, Google your name and make sure you don’t look too embarrassingly drunk in your Facebook page, but most responsible companies will perform more than cursory background checks, and there’s quite of bit of data that can come into play:
- Employment–social security data, Workers’ Compensation records, state licensing records (for medical, dental, legal, financial and other professionals, as well as for workers who care for children, the elderly and the disabled)
- Legal–court records (which may include criminal cases as well as a plethora of civil-litigation information), prison records, parole records, sexual offender lists, drug testing records, property ownership data
- Education–grades, academic probation records, honor code violations, student employment records, student housing and university police records
- Military–honorable or other discharges, records of service, dates of service
- Financial–credit reports, banking reports, bankruptcy records
- Auto-Related–driving records, vehicle registration records
- Character references from former employers, supervisors, co-workers, educators, neighbors, vendors, employees and others
- Medical records
(The Fair Credit Reporting Act disallows inclusion of the following in background checks: records of civil suits or judgments, paid tax liens, accounts placed for collection, and records of arrests, after 7 years; bankruptcies cannot be reported after ten years.)
Most employers would be hard-pressed to investigate all of these resources on their own, so they turn to Lexis-Nexis and ChoicePoint. Both companies are categorized as credit reporting agencies (CRAs) under the Fair Credit Reporting Act, meaning that you should have access to a free report annually and whenever you suffer an adverse action, and that you have the right to dispute errors and have them investigated and corrected. And, as with the insurance and medical reports we’ve discussed previously, you do have to provide written permission for a prospective employer to obtain many of these reports about you, including education, medical, and military records.
If you know you’ll be undergoing a background check for employment, there are many things you can do to check–and even hose off the mud from–your paper trail. While you’re waiting to receive your Lexis-Nexis and ChoicePoint consumer reports, which can sometimes take 30 to 60 days, check out the reputation-enhancing suggestions offered by the Privacy Rights Clearinghouse.
Don’t don’t forget to clean up the dirt on your digital paper trail, as well. The e-Justice blog has a great post on “Who Knows What About You? 25 Free Tools To Find Out”. (And take those Spring Break photos off your Facebook page!)
To get your consumer reports and find out what prospective employers will see:
Lexis-Nexis
1. Go to Lexis-Nexis. (Navigation to this link can be difficult. If you are ever unable to click directly, use the site map for http://www.lexisnexis.com to find the privacy section and then locate the “For Consumers” button.)
2. Click on Personal Information Request.
3. Review the two lists of items you may use to validate your identity via your Social Security number, name and current address.
–From the first list, you may select to send a photocopy of any of the following: your Social Security card, W2 form, military identification, a current pay stub (if your SSN is listed) or any other document containing your SSN.
–From the second list, to prove your address, select a photocopy of your driver’s license (front and back) or a recent (within the past two months) utility, phone or credit card bill.
4. Print the Lexis-Nexis “Request for a Accurint Report” form.
5. Submit your form with photocopies of your identification to:
Accurint Consumer Inquiry Department
P.O. Box 105610
Atlanta, GA 30348-5610
ChoicePoint
ChoicePoint is a Lexis-Nexis partner, so don’t be surprised to see Lexis-Nexis logos on their pages, as well.
1. Go to ChoicePoint.com
2. Select “Access to Your Personal Information” from under the Reports About You section.
3. Read the Instructions for Requesting Your ChoicePoint Full File Disclosure. You’ll see the proof of identity and name/address submissions are largely identical to those listed for the Accurint/Lexis-Nexis report.
4. Print the Full File Disclosure Request Form and fill it out accurately.
5. Send copies of your identity validation documents and completed form to:
ChoicePoint Consumer Center
Attn: Full File Disclosure
P.O. Box 105108
Atlanta, GA 30348-5108
(Note: this is NOT the same address as listed for Lexis-Nexis, though they are similar.)
LANDLORDS
When you go to rent a new apartment or house, the owner has a vested interest in making sure you’ll pay your rent on time and not turn his little loft or cottage into a crack den. Under most circumstances, a prospective landlord will pull your credit report; less often, depending on whether it’s one duplex or a corporate-owned complex of hundreds or thousands of apartments, a landlord or leasing office may pull a complete background check.
However, another set of resources is available specifically for mid-sized (or “multi-family”) property management offices. SafeRent and Rent Bureau collect and distribute a wide variety of rental application and personal data, including rent payment histories, references, credit ratings, and criminal record reports. They even have scores designed to predict the relative risk of a tenant turning rock-star and trashing the apartment, disappearing in the dark of night without paying owed rent, bouncing checks or otherwise acting in such a way that landlords will be inclined to start eviction proceedings.
Before you rent, be sure you know what your paper trail says about you:
SafeRent is the big player in rental records, operating a database of over 34 million records based on reported landlord-tenant histories.
1. Go to FirstAdvantage SafeRent.
2. Click on Consumer Relations.
3. Read through the explanations of the different types of files, then click on Consumer Disclosure Request Form in the body of the first paragraph.
4. Read through the requirements carefully. Note the circumstances under item #2 wherein you can receive a free annual report even if you have not received an adverse action notice (i.e., even if you haven’t been denied housing).
5. Complete the form and make photocopies of your proof(s) of identification. As explained on the form, you may send a copy of your current driver’s license or government issued ID, or copies of any two of the following: your Social Security Card, a non-government issued ID (like an employee or student ID), or a recent utility bill. Paper Doll advises against mailing copies of your Social Security Card whenever avoidable.
6. Send the form and proof(s) of identification to
FirstAdvantage SafeRent, Inc.
Consumer Relations Department
7300 Westmore Road, Suite 3
Rockville, MD 20850-5223
SafeRent should mail your report within three days of receiving your request.
If you have further questions, you can call 800-815-8664.
Rent Bureau maintains a database of approximately six million lessee records.
1. Go to RentBureau.com/Consumers.
2. Click on Credit File Request form to get a copy of your Rent Bureau Rental File.
3. Fill out the basic information and mail it to:
Rent Bureau, LLC
P.O. Box 18706
Atlanta, GA 31126
There is also a fax number listed, but Paper Doll advises against faxing personal information, particularly Social Security numbers, whenever possible. It’s just too easy to mistype a number and send your private information where it does not need to go.
YENTAS (Matchmakers) and OTHERS
While it may seem that matchmakers have gone the way of the dodo in this generation of eHarmony, Match.com and OK Cupid, there are still a great number of personalized introduction services out there, and one of the reasons they can charge the high rates they do is because they purport to do a complete background check on every applicant.
Earlier this year, the NFL Players’ Association, a union of professional football players, chose not to select former NFLPA President Troy Vincent for the position of Executive Director after the Associated Press completed an exhaustive investigation into Vincent’s business dealings based on public records, financial statements and personal interviews. While finding no wrongdoing, per se, the NFLPA opted to go with a candidate not weighed down by controversial business dealings which some members felt could expose Vincent to lawsuits and distract him from important NFLPA work.
More and more, our lives are led in public, and very little can remain hidden or private. Paper Doll believes that in some ways, sunshine is the best (figurative) disinfectant, but in other ways, discretion is the better part of valor. Either way, our employment and financial futures will increasingly depend on the information about us that is collected and distributed by third parties. The best we can do is make sure our paper trails are accurate (and hopefully, squeaky clean).
Next week, we’ll complete the “Who Knows Your Secrets?” series with important information just in time for you to head out for post-Thanksgiving Day shopping (and the inevitable returns).
Who Knows Your Secrets? Part 4: Someone’s Snooping in Your Medicine Cabinet!
Of course, insurance companies aren’t only interested in damage claims for your home and car. They also want to take your temperature, so to speak, as a prospective health insurance customer, so they track your health and medical claims history, including some things that might surprise you.
MIB–NOT THE “MEN IN BLACK” BUT JUST AS POWERFUL!
The Medical Information Bureau (MIB) is the biggest weigh station along your health-related paper trail. If these Men In Black namesakes seem vaguely familiar to you, it might be because we referenced them last year, when we talked about medical identity theft.
The MIB compiles and maintains records concerning individual health insurance, as well as disability, long-term care, and life insurance. Your MIB report includes all the information you would have reported when filling out an application to purchase insurance. It also includes whatever data the insurance company can obtain from your doctors, nurses, midwives, hospitals and other healthcare providers–anything that references any kind of medical condition that insurance companies would consider important or “significant”.
According to the Privacy Rights Clearinghouse, the MIB has over 230 numerical codes to indicate specific medical conditions, to which their computer algorithms assign a risk value.
Your MIB report might include information regarding blood pressure, diabetes, asthma, obesity or ongoing reproductive issues, obtained from your insurance company directly via your health care providers but there also may be behavioral data that your insurance company learned of obliquely (perhaps as a result of an emergency room visit). This means that they might collect information about you regarding anything from smoking to participation in extreme sports like bungee jumping or hang gliding.
Depending on the depth of collection and reportage, an MIB report might even contain data regarding a poor driving record or drug-related criminal activity not involving drug use. (Paper Doll can imagine how being a drug kingpin might put one at risk for all sorts of molten lead-related injuries). And from all of this collected data, your insurance risk is determined.
Not everyone has a current MIB file. In general, you will only have a file if you applied for health-related insurance (including disability, long-term care and life insurance) within the last seven years, and only if you applied as an individual; if you applied as a member of a group (i.e., you got a new job and signed up for insurance through work), it doesn’t show up in your MIB file. You also won’t be likely to have an MIB report if you haven’t had any kind of “significant” medical condition in the last seven years, where a “condition” could be an illness, injury, pregnancy, etc.
In theory, insurance company databases should be a good thing. As with the CLUE and A-PLUS reports, MIB’s database exists to help insurance companies detect and eliminate fraud on insurance applications; for example, if there’s a discrepancy between someone’s self-report of no history drug abuse and a previous notation about such things in a medical record, the MIB should catch it.
Again, in theory, keeping accurate information keeps corporate costs down by purging fraud and abuse out of the system, which should keep costs lower for us as consumers. In actuality, however, none of the agencies compiling and reporting on our various medical and behavioral paper trails are perfect. Inaccuracies in our reports, whether the result of unintentional keystroke errors or medical identity theft, mean that we not only might end up paying more (possibly more than we can afford) for health insurance premiums, it could make it hard to get insurance at all–current indeterminate health care reform legislative activities notwithstanding!
Thus, as with our credit, banking and other insurance reports, it’s essential to know if the MIB has a file on us, and if so, what’s in that medicine cabinet of records.
To get a copy of your MIB consumer file (if you have one), call 866-692-6901, toll-free. Canadian residents can request free MIB reports by calling 416-597-0590 (long distance charges apply) or by downloading a Request for Disclosure Form in English or French.
To learn more about requesting your file, visit the MIB web site.
PRESCRIPTION DATABASES–ASSUMING FACTS NOT IN EVIDENCE
The MIB aren’t the only ones who know what’s going on in your health history. IntelliScript and MedPoint maintain databases solely about patients’ prescription drug purchase histories, develop a pharmacy risk score, and report the data to insurance companies. The higher the score, the higher the potential cost for the insurance company to cover the patient. Officially, the pharmacy risk score isn’t personal; the companies say the scores represent an expected risk for any particular group (evaluating variables such as age, gender, and specific pharmaceutical-use histories). As with the MIB reports, the IntelliScript and MedPoint reports generally come into play when you try to purchase private health, disability, long-term care or life insurance.
What the reports don’t note (and which can only be learned directly from your healthcare practitioner’s notes), is WHY you were prescribed particular medicines at particular dosages, and that can present a problem. Physicians often prescribe medicines for off-label purposes or for alternative reasons: the anti-depressant Prozac can also ameliorate hot flashes in menopausal women, oral contraceptives can fight PMS and PMDD, beta blockers (normally prescribed for hypertension and cardiac care) reduce the incidences of chronic migraines, and so on. Insurance companies make inferences from your IntelliScript and MedPoint drug histories, assuming facts not in evidence.
So, you could be prescribed a medication to improve your quality of life that is more commonly used to combat more serious conditions. However, your report won’t tell prospective insurers that. With your drug prescription and refill history on display, a decision-maker at an insurance company (possibly even a computer, programmed to assign risk factors to prescription meds entered by code), may make flawed assumptions about your medical conditions to assess the risk of underwriting your insurance policy.
HIP, HIP, HIPAA CONCERNS
Flawed inferences regarding prescription purposes? Data entry errors and medical identity theft? What else makes these databases problematic? How about potential violation of HIPAA regulations? The companies claim that personal prescription data is only released with the consumer’s authorization, ostensibly in the form of a small print waiver in a health insurance application form.
However, since neither Milliman nor Ingenix (the parent companies of IntelliScript and MedPoint, respectively) are covered by HIPAA, the HIPAA regulations don’t give the Department of Health and Human Services the authority to directly investigate their activities or hold the companies responsible for what they do with the data they collect. As reported by The Washington Post and other media outlets, there is even fear among the consumer advocacy community that there’s at least potential for IntelliScript and MedPoint to repurpose the collected, aggregate data to help pharmaceutical companies market drugs.
YOUR ROLE AS CONSUMER
Never heard of IntelliScript or MedPoint’s prescription databases before now? Don’t feel bad–most people hadn’t until two years ago, when the Federal Trade Commission successfully sued Milliman and Ingenix, to force them to comply with the Fair Credit Reporting Act. The FTC prevailed in defining them as credit reporting agencies (CRAs) just like Equifax, Telecheck and the other agencies we’ve been discussing in this blog series, because they collect and evaluate consumer report information for the specific purpose of distributing it to third parties–in this case, health-related insurance companies.
So, based on your IntelliScript or MedPoint report, an insurer could increase your health, disability, long-term care or life insurance premiums, deny coverage for certain conditions, or deny coverage altogether. Yikes! But now, if you are denied coverage or charged increased premiums, the Fair Credit Reporting Act gives you a variety of consumer rights to gain access to your reports via your insurance company, and dispute inaccurate information or flawed inferences (if you can figure out, from your report, what inferences were drawn).
And, even if you haven’t experienced what the FCRA calls an adverse action (as we discussed last week), if you’ve applied for individual (not group) health-related insurance, you can request one free report annually, directly from both IntelliScript and MedPoint.
To request your free reports:
- Call IntelliScript at 877-211-4816.
- For information regarding alternate methods of contacting IntelliScript, check out the contact information on the web site.
- Call MedPoint at 888-206-0335 or
- Write to:
MedPoint Compliance
Ingenix, Inc.
2525 Lake Park Blvd
West Valley City, Utah 84120.
For either report, expect to provide detailed information, including your full name, date of birth, the last four digits of your Social Security number and your zip code. Your report will include a copy of any information they’ve collected about you, in addition to a list of the names of all the insurance companies that have requested your report.
Rather than waiting for an adverse action notice to trigger your FCRA rights, be proactive. If you’re thinking of applying for new health insurance, long-term care or disability coverage, or life insurance, plan ahead and order your MIB, IntelliScript and MedPoint reports. If nothing adverse comes up (or nothing at all, in the case of the MIB), great! But if you find flaws or errors, it’s much better to dispute them and have the reports corrected before you try to access urgently-needed coverage.
Third-party electronic collection and analysis of personal medical data is a growing field. Beyond the collection of health care provider notes and pharmaceutical records, companies are already in the process of testing methods for collecting data from commercial labs to add to the insurance industry’s arsenal of risk predictors.
As always, it’s essential for you to be your own best advocate and know who’s following your paper trail.
Who Knows Your Secrets? Part 3: Get A CLUE About Insurance Reports
Oscar Wilde may not have known it, but his statement is applicable to how much of a mystery our own financial “secrets” can be, even to ourselves. Sure, you may be skilled at sussing out that Colonel Mustard did it in the library with the candlestick. But what if Mrs. Peacock, the agent from your insurance company, Mustard Mutual, canceled your homeowner’s policy with a pen stroke? Would you know why, or what it meant?
As we’ve been discussing over the past few weeks, just by going through our daily lives, someone gets to collect a paper trail of information about our activities. Consumers tend to know about credit reports and FICO scores, but are less likely to know about the various Big Brother agencies (TeleCheck, Checks Systems and EWS) keeping tabs on banking and checking habits.
We tend to worrying about dumpster-diving identity thieves, but it turns out that there are many others out there legitimately (if inaccurately) gathering and disseminating information about us. Indeed, the more Paper Doll digs, the more it seems that when it comes to consumer awareness of insurance paper trails, nobody has a clue!
CLUE is the Comprehensive Loss Underwriting Exchange, operated by ChoicePoint, a division of ChoiceTrust. CLUE maintains a huge claims history database of basic policy information, including name, date of birth, policy number(s), plus various claim information, including the date of loss/damage, type of loss incurred, the amounts paid to the policy holder (or, occasionally, to another party), and a description of the property covered. Claims information generally goes back anywhere from three to seven years.
No mystery, right? All this data enables insurance companies to access past claims information when they’re risk-rating, underwriting or renewing an insurance policy. Unfortunately, as with most of the reports developed by third parties, information about us is not always accurate or complete.
TAKING THE FALL FOR SOMEBODY ELSE
Take, for example, Jim Deck of Nashville, TN. He was notified of a huge increase in his renter’s insurance due to adverse information in his CLUE report, which included a reference to a car accident where an insurance company paid out a significant amount on a policy. The only problem? The car in the reported accident wasn’t Mr. Deck’s, but his mother’s, and he hadn’t resided at the same address as his mom in 13 years. The record of an accident claim by someone at the same address can end up on the wrong person’s report.
Not worried? You might want to reconsider that. Even if your parents, your post-college roommates, or your current spouse all have blemish-free insurance records, if people who lived in your apartment before you rented, or bought your home after you moved, total strangers (because they reside or resided at the same address as listed on your CLUE report–even if you never lived there at the same time) could prevent you from getting insurance or cost you an arm, leg or other beloved body parts in increased interest rates.
THE CLAIM THAT NEVER WAS!
The CLUE report may also include negative information resulting from claims you decided not to make! Let’s say you call your insurance company to make an inquiry as to whether something would be covered–perhaps water or smoke damage–but then never make a claim. Maybe the cost of repairs would be less than the cost of your deductible; maybe you were just worried about what that ice storm brewing outside might do to your roof.
If your little call is reported by your insurance company to the Comprehensive Loss Underwriting Exchange, unless you reside in a state that forbids such practice, your policy could be canceled, failed to be renewed or have rates increase…all because of an inquiry that never even led to a claim!
It’s not just the little guy who suffers; distribution of inaccurate information is an equal opportunity experience. According to the Privacy Rights Clearinghouse, at an August 4, 2003 press conference on unfair insurance practices, the California Insurance Commissioner reported that the Chief of the Consumer Services Division of California’s Department of Insurance was turned down when he tried to insure his new home. A seriously flawed CLUE report showed five claims: two were for properties the seller owned in a different city, two were coverage inquiries that never resulted in actual claims, and the final claim was resolved and shouldn’t have been used to determine his eligibility in the first place.
(Paper Doll imagines, though, that the Chief of the Consumer Services Division of the California Department of Insurance probably got expedited assistance. I don’t envision the Chief listening to The Girl from Ipanema on ChoicePoint’s on-hold Muzak for hours on end.)
YOUR DREAM HOME BECOMES A NIGHTMARE
If you’re considering buying a home, you’d want to know what kinds of homeowner insurance claims have been made against it. First, you’d want to know if there are any recurring problems (flooding, roof damage from neighboring trees, etc.) that make the home less attractive or will cost you higher insurance premiums.
Beyond that, even if you’ve never, personally, made an insurance claim, if a property comes with its own history of repeated claims, such as for water damage, the property itself could be blacklisted, preventing you (as new owner) from getting insurance coverage at any cost!
The U.S. Fair Credit Reporting Act only allows CLUE reports to be accessed by the owner, insurer or mortgage institution for the property. However, before you buy the house, you can request that the current owners of the property order and provide you with the CLUE report for the house. (You might be doing them a favor; if they’re like most consumers, they probably don’t even have a clue…about their own CLUE report.)
CLUE’S PARTNER IN CRIME
Insurance companies use two main tools to determine how likely you are to file a claim on your policy:
1) Your CLUE report; and
2) Your insurance score is based mostly on your credit score, along with other public records information. Yes, it may seem that the insurance companies are assuming inability to pay bills on time makes one more likely to have hail damage, but it’s not always so simplistic.
Because credit scores include records of personal bankruptcies, tax liens, garnishments (for taxes, child support payments, etc.), foreclosures, and civil judgments, the insurance companies feel they can get a pretty good feel for a potential policy-holder’s ability to honor the payment contract and deal honestly with regard to making claims.
Different insurance companies use different models to develop insurance scores, so it’s a good idea to ask your agent (or prospective agent) about the model his or her company uses. Because the ways in which insurance companies use credit information can vary widely, a good resource for understanding all the issues is Consumer Brochure — Alaska: Understanding How Insurers Use Credit Information.
Paper Doll leaves it to you readers to decide how predictive you think even accurate credit score information is in the development of a score to determine insurance risk. Nonetheless, various states have passed laws curtailing the use of credit report data in insurance scoring, and the Federal Trade Commission has ordered nine major insurance companies to submit information regarding their use of credit reports in determining insurance scores.
With these two factors determining how (and at what rates) you can get homeowner’s and auto insurance coverage, it’s time to get a clue…about your CLUE! In fact, professional organizer and Daily Money Manager Nanette Duffey says, “Knowing and understanding the contents of your CLUE report provides useful and no-cost information to consumers. Reviewing your report, especially after experiencing a significant insurance claim, is empowering. I consider it one more step towards becoming a financially savvy and confidant consumer.”
GET YOUR CLUE REPORT
Because ChoicePoint, the major provider of property loss reports, including those generated by CLUE, is considered a consumer reporting agency under the FACT amendment to the Federal Credit Reporting Act, you have some consumer protection. This means you can order a free copy of your CLUE report, annually. To obtain your report:
- Go to ChoicePoint’s ChoiceTrust.com page.
- Click on “Review Your FACT Act Disclosure Reports” and register as a new member.
- Once you’ve registered, click on the “Personal Insurance Reports” link at the top of the resulting page.
- Select “Learn More” on either the CLUE Personal Property report or the CLUE Auto Report. (Don’t click on the lower level, where they combine the free CLUE report with an insurance report, as that option is not free).
- Select “Both Reports” under Order Options and then provide multiple screens of personal information–including answers to an “Identity Information Quiz” to prove that you actually are who you say you are. (You didn’t think they were going to make this easy, did you?)
- Print your order confirmation…but DON’T CLOSE THE WINDOW. This report is designed to be viewed online, and you’ll have access for only 30 days, so click the “Continue” button to view (and print) your reports.
You may also call 866-312-8076 or mail your request to:
C.L.U.E. Inc. Consumer Disclosure Center
Attn: FACT Act Request
P.O. Box 105295
Atlanta, GA 30348
ChoicePoint will then send you a form you can fill out and return by mail.
The Federal Credit Reporting Act also ensures that, over and above this free report, if you are ever denied homeowner’s or auto insurance, your policy is canceled, your coverage is limited, or your premiums significantly increase, you are entitled to an additional free copy of your report.
If any of the above occur, your insurance company must provide you with an adverse action notice. You’ll have 60 days from receiving the notice to request your free CLUE report. Upon receiving it, you can dispute any inaccurate or incomplete information and ChoicePoint must investigate and correct any errors; if you’re dissatisfied with the results of the investigation, you have the right to file a statement to that end, which will appear in all future reports.
A-PLUS
Finally, while ChoicePoint’s CLUE report is the major suspect in the mystery of your insurance paper trail, Insurance Services Office (ISO) does offer its own, lesser-known competing report, based on information reported by over 1,400 insurers to the Automobile-Property Loss Underwriting Service…also known as the A-PLUS. These reports are governed by the same Federal Credit Reporting Act FACT dispute policies as described above in the CLUE section, so it’s definitely worth your time to obtain your report annually and if you ever receive an adverse action notice.
A-PLUS reports can’t be downloaded or viewed online; rather, they are mailed within 15 days of a request. To order your own A-PLUS report, call 800-627-3487. For more information, you can visit ISO’s A-PLUS page.
Readers, please solve the mystery of your own insurance paper trail: get a CLUE and earn an A-PLUS.
Who Knows Your Secrets? Part 2: Checking Up on Your Checking History
But wait, there’s more! (Lots more!)
You already know that the three credit reporting agencies (Equifax, Experian and Trans-Union) keep track of all the activity on your credit cards, mortgages, loans and medical accounts. But they aren’t the only ones checking out how and where you spend your money. For years, two companies, TeleCheck and Chex Systems, have been tracking negative consumer checking activity and reporting the information to banks, credit unions and other financial institutions. They also serve retail companies, verifying the validity of checking accounts and helping calculate risk associated with checks written to merchants.
According to a 2008 Identity Fraud Survey Report conducted by Javelin Strategy & Research, “new account” fraud cost the financial services industry $14.7 billion in 2007 and cost the victims an average of $1,066 per case. Thus, it’s understandable that banks seek help to screen applicants for new bank accounts for any kind of history of abuse or financial fraud. Because retail stores suffer from account fraud as well, they require services for verifying identification and dealing with risk management.
That’s where TeleCheck, Chex Systems, and one newcomer, EWS, come in.
Chex Systems operates as both a check verification system and a consumer credit reporting agency (and as such, is governed by the Fair Credit Reporting Act, as we discussed last week), collecting and reporting data regarding consumer banking habits, bounced checks, overdrafts, deposits of fraudulent checks, and general suspicious account activity.
Approximately 80% of U.S. banks and credit unions subscribe to one or more of the Chex Systems reporting services to help them determine whether you will be allowed to open a checking or savings account. Just one negative item in your Chex Systems profile will likely close bank doors to you, and negative reports stay in your profile for up to five years.
Also, many consumer advocates have concerns about Chex Systems’ practices, claiming that unlike Equifax, Experian and Trans-Union, which collect and report both positive and negative elements of a person’s financial history, Chex Systems reports only negative data. Various websites and blogs, such as StopChex.com, have been developed to help consumers deal with issues related to Chex Systems and to identify banks that do not use Chex Systems’ services.

TeleCheck, a FirstData company, operates check verification and risk analytics services for retail stores, utilities and other organizations. For most people, their first awareness of TeleCheck might come if a cashier reports that a check transaction has been declined. The cashier will then give the customer a “courtesy card” with a contact number for TeleCheck, a seven-digit record number for the transaction, and a code to help TeleCheck determine the reason for the decline.
The frustrating thing for many consumers is that while TeleCheck does not provide the cashier (or even the retail establishment) with any information regarding a person’s bank balance, it still feels like a stinging rejection. The customer may have a history of bounced checks…or it could merely be the result of TeleCheck not having enough information about the customer on file!
TeleCheck’s computers have various “risk models” in place to analyze transactions, and if TeleCheck lacks the data to make any predictive risk assessment, any check processed via TeleCheck will be declined. (It’s like rejecting any and all prospective computer dating matches if no photo is supplied…only it’s done in public, while you’re in line, surrounded by friends, neighbors and cranky shoppers.)
If there’s nothing actually wrong with your checking history, TeleCheck claims they can “help you establish a positive file” by providing them with the record on the courtesy card, your driver’s license information, the bank routing and account numbers at the bottom of the check, and, if a bank (rather than a retail outlet) rejected the check, your Social Security number, as well. As of yet, there’s no request for blood type or preferred pizza toppings.
It’s bracing to think that a company you’ve probably never heard about can wield so much power. However, an advantage of TeleCheck seems to be that if there is some question regarding unpaid check debt, once the vendor confirms that the debt was paid (even if you did originally make a banking error), TeleCheck will remove the item from your record. (Otherwise, records of unpaid check debt stay on your TeleCheck profile for seven years.)
Early Warning Services, or EWS, the new kid on the block, was created as a jointly owned venture of Bank of America, JPMorgan Chase, BB&T Corporation, Wachovia, and Wells Fargo. Like Chex Systems and TeleCheck, EWS also collects data about consumer banking activity, primarily bounced checks and excessive overdrafts.
You might think that if you’ve never bounced a check, you’d be safe. It isn’t quite that simple.
The problem? As with credit histories, the information being collected about you may be incorrect, either because of the nefarious activity of someone who has stolen your identity or merely because someone along the financial food chain mistyped a digit and linked your good name with someone else’s checkered past.
What can happen if erroneous information (either due to identity theft or clerical error) gets included in your TeleCheck, Chex System or EWS profile? Retailers could refuse to accept a check you present for payment.
Imagine the embarrassment of finally getting to the front of a checkout line to buy a week’s worth of groceries or a whole slew of holiday gifts, presenting your check and identification, and having the cashier call over the manager to explain, in a voice loud enough for the people behind you to hear, that your check will not be accepted.
Or, imagine being dissatisfied with your current bank, or moving to a new city and needing to open up an account with a bank with local branches, only to find that your bank of choice is refusing to open a new account because of so-called negative activity in your profile.
In the past, someone with a spotty banking history could shop around for a small bank or credit union that did not subscribe to the Chex Systems or TeleCheck services. However, with the advent of EWS and the increased need for financial institutions to fight fraud, it’s highly unlikely that someone with a damaged record would be able to either beat the system or blissfully ignore trouble caused by an identity thief. Thus, as with checking your credit reports (and score) annually, it’s essential you know who knows your checking “secrets”.
To obtain free copies of your reports, go to:
Chex Systems and then click on “Order Consumer Report” and follow the prompts.
TeleCheck and then click on “TeleCheck Consumer Assistance”. Then click on “Request Your TeleCheck File Report”, select “Annual File Report” and provide the requested information.
Early Warning Services Call 800-325-7775. Currently, there’s no way to request a copy of your report online.
Of course, just ordering these reports and not doing anything about them is about as helpful as buying exercise DVDs and putting them on a shelf. Carefully review each entry and dispute any errors, both with the reporting agency and, if applicable, a merchant or creditor. The Fair Credit Reporting Act requires that reporting agencies take action within 30 days to investigate the errors you report, so mark your calendar, stay alert and be vigilant about correcting any inaccuracies.
To keep negative items from appearing in your Chex Systems, TeleCheck, or EWS profiles , you’ll want to take the following precautions:
1. Balance your checkbook. Yes, really. Financial responsibility begins with knowing how much money is in your checking account. Reading your monthly statement (or checking it periodically online) and reconciling with your own records makes it far more likely you will catch near-overdraft balances and incidences of identity theft.
2. Understand that there’s no such thing as “float“ anymore, especially since the 2003 passage of the federal Check 21 Act. Assume the money is gone from the account the moment you write the check, instead of hoping it will take a few days for a transaction to be finalized, and you’ll eliminate your risk of overdraft.
3. Know that deposits will not always clear immediately. If you deposit one check and write another check on the same day, don’t assume the deposit will be credited to your account before the check you wrote gets debited.
4. Know your bank or credit union’s policies regarding crediting and debiting accounts. Many banks have a policy of applying daily debits from largest to smallest. In such cases, you are far more likely to have multiple overdraft fees (which further decrease the balance in your account).
Let’s say you have $2500 in your account. In the span of two days, you deposit $1500, write checks for $1800 for your mortgage, $300 for your insurance payment, and $100 for utilities, then made four ATM withdrawals of $50, four debit card purchases of $25 and five of $5 each. If your bank tends to hold deposits even two days, your total amount debited would be $2525, or $25 more than your balance (as your deposit would not yet have been credited). However, if your bank processes daily checks and debits from highest to lowest, each of your $5 purchases would incur an insufficient funds fee of, for example, $39. Thus, instead of having a negative account balance of $25, you’d have -$220. Ouch!
5. Don’t close any checking account until you make sure all checks have cleared and that you’ve canceled all repeating auto-drafts, automatic transfers and/or debits, and that you’ve paid all applicable bank fees.
6. Notify your bank if replacement checks you’ve ordered fail to arrive, or if the box(es) appear to have been opened, even if no checks are missing. Identity thieves find sneaky uses for the information they purloin; you’ll want to change your bank account number right away.
Finally, if adverse information in your Chex Systems, TeleCheck, or EWS profiles is the result of your own past financial mistakes (other than fraud), there is an alternative that will help you erase your blacklisted status and open a checking account.
Checking Network USA, an FDIC partner, offers a series of classes and workshops on financial responsibility. If someone takes and passes the courses (whether online or in a classroom setting) and is granted certification, checking account access to Checking Network USA’s partner financial institutions is eased.
See you next week, for more in our ongoing series on who knows your secrets and who is following your personal paper trail.
Follow Me