Paper Doll
Organizing Your Tax Paperwork–Part 2: Health, Home, Heart & Head
Last week, we talked about the information return documents (W-2s, 1099s and 1098s) that delineate how much money you’ve received (from employers, financial institutions, etc.) and how much you’ve paid (either directly or indirectly) in various federal and regional taxes. But that’s just the beginning of your paperwork.
Then there are documents you received (and should have saved) as a result of some kind of transaction–receipts or records essential for completing personal or family taxes. Today’s post reviews which documents you should locate to complete your 2009 returns, and which you can begin collecting to make next year’s tax preparations even easier.
But first, do you have everyone’s Social Security cards? Sure, you’ve probably had your own number memorized since you took the SATs, but are you certain you know your spouse’s number? Your children’s? The elderly relative for whom you are the sole support? If you pay alimony, do you know your ex-spouse’s number?
A major cause of audits is a mismatch between information provided to the IRS by third parties (e.g., via W-2s and 1099s) and that provided by you. If a Social Security number is off by even one digit, it impacts not only your likelihood of being audited, but also your earnings history, and therefore, your eventual benefits.
So what documents do you need? There’s financial proof that is (or should be) delivered directly to you via some kind of correspondence and proof that you must retrieve at the time of a transaction, for various categories:
- Your Health
Medical insurance company summaries of out-of-pocket health expenditures for last year might be a goldmine if your family’s medical expenses were high. Unlike miscellaneous deductions, which need only combine to 2.5% of your adjusted gross income, medical expenses must exceed 7.5% of your AGI to be deductible–otherwise, you’d just take the Standard Deduction.
If your insurance company doesn’t automatically mail monthly or annual summaries, call to find out if there’s a way to log into your account to access and print a 2009 summary (and save you a lot of math). If not, you can usually use the “You Owe” column of the Explanation of Benefits your insurer sends after doctor’s visits, hospitalizations and procedures. This will give you a handle on which receipts or dated statements you’re seeking.
Be vigilant about saving medical expense receipts, as your EOB’s and insurance company summaries are not legal proof of what you spent on deductible medical expenses, only indications of what you owed to medical providers. Collect receipts for:
–Traditional medical expenses–Be sure you’re counting only medical expenses you paid and not portions paid by the insurance company or in the section on the Explanation of Benefits generally referred to as network savings. (That amount isn’t something you paid, or even something paid by the insurance company. It’s the amount knocked off the bill simply because you have insurance. If you were uninsured, you’d be charged more than the combined total normally paid by you and the insurance company. Oy!)
–Pharmaceutical expenses–Did you know you can call or go into your pharmacy and request a printout of all pharmacy purchases you made for yourself or your children? This is a major organizational advantage of using only one pharmacy–one printout. Because of privacy laws, your spouse may have to make a separate request.
–Health Savings Account documentation–For every qualified medical expense you pay through your health savings account (HSA) or medical savings account (MSA), it’s essential to keep a record of the name and address of each person or company you paid and the amount and date of the payment. Since HSAs can be used to cover everything from orthodontia and acupuncture to durable medical equipment and contact lens solution, be sure to save your receipts, and if a receipt doesn’t clearly describe what you actually purchased, make a note at the top to ease your labor at tax time.
–Medically-necessary travel expenses–Did you know that if you (or a family member) have conditions that require travel for treatment, you can deduct the travel costs? Either keep a log of the miles you drive your car for medical purposes and use the standard mileage rate, or, if you have a penchant for minutia, you can record gas and oil expenses directly related to any medically-necessary travel.
- Your Home
Home purchases–This year, with so many taxpayers taking advantage of the $8000 First-Time Homebuyer Credit, the issue of home purchase record-keeping is especially important. Be sure to maintain records regarding the purchase (or sales) documentation for a house, as well as records for closing costs, home inspections, fees paid to real estate agents and any records regarding private mortgage insurance.
Casualty and theft losses require documentation. For thefts, you’ll need to have proof of ownership (that’s why we recommend saving “big ticket” item receipts and videoing a household inventory), proof of theft (usually via a police report) and the date that the item is believed to have been stolen (to be sure it falls in the appropriate tax year).
For proof of loss due to casualty, you’ll want to maintain insurance company confirmation letters regarding the date and cause (ice storm, lightning, fire, auto accident, etc.) of loss, estimates of original costs and costs of repair/replacement vs. what your insurance company will or will not pay (or has paid), and proof of ownership.
Moving expenses relate to actual costs (movers, truck rental, storage, etc.) and mileage. Did you move more than 50 miles in order to work at a new job location? Check out IRS Publication 521 regarding what you’ll have to document.
Other home-related paperwork to save:
–Receipts and records regarding any home improvement efforts you’ve made which materially increase the value of your home (which will have a tax implication when you sell)
–Records of purchases for your primary residence that qualify you for the Energy Star tax credits this year–This gives you credit for 30% of costs up to $1500 worth of energy-efficient purchases, including biomass stoves, various heating/air conditioning devices, insulation, water heaters and windows and doors.
- Your Heart (Loved Ones and Philanthropy)
Childcare/Eldercare costs–To take advantage of the Child (or Dependent) Care Credit, you’ll need documentation of the name, address, and Taxpayer/Employer Identification number for any care provider you’ve used for your kids or other dependents. Whether you’re using a babysitter from down the street or employing the services of a daycare facility (for either children or adults), use federal form W-10, Dependent Care Provider’s Identification and Certification.
Plus, even if you’re not planning to run for elected office, be sure you’re not running afoul of Nanny Tax requirements regarding FICA (Social Security and Medicare) and FUTA (unemployment insurance). Keep records of what you paid (and when), what you withheld and what you submitted to the IRS.
Confirmation of donations from charitable agencies–You may get a nice form letter on the non-profit’s stationery, or they may bury your acknowledgment as tiny text in asterisked comments at the bottom of requests for further donations, so you really do need to be diligent about opening your mail. A confirmation should include the name of the qualifying charitable entity, a date of donation or at least the date of the acknowledgment (i.e., something to prove the tax year of the donation) and a dollar amount or a description of materials, if an “in-kind” (non-monetary) donation was made.
Not every charity confirms donations in writing. In past blogs, I’ve noted that for your protection, you should keep a “Tax Prep-Charity” folder into which you put documentation of any donations you make. If a charity sends you requests for money and you return a check or credit card authorization with the payment stub, use the rest of the page to mark the date, dollar amount and method by which you paid (check number or credit card name), and file it away.
- Your Head (Hobbies, Jobs, and Education)
Education expenses can be deducted in a variety of ways too numerous (and complex) for this arena–and then there are credits (the Hope Credit, the Lifetime Learning Credit, the American Opportunity Credit), Savings Bond programs and more. In addition to keeping your 1099-T (for tuition) and 1099-E (for educational interest), be sure to maintain transcripts that show your periods of academic enrollment, as well as canceled checks, credit card statements or other receipts that verify the dates of purchase and amounts you spent on tuition, books, lab materials, student fees, etc.
Notice of gambling or lottery winnings should come via W-2Gs, but even if a casino or lottery agency doesn’t send you a notice, you can be sure the government knows about your winnings. They certainly don’t know about your losses, however, which is why, if gambling is a big part of your lifestyle, you’ll want to keep a diary of your gambling losses to offset your winnings.
To deduct your losses, the IRS requires that you must be able to provide receipts, tickets, statements or other records that show the amount of both your winnings and losses. They’d like your diary to include the date and type of gambling activity, the name and address where you gambled (apparently “Joe the Bookie” isn’t going to suffice), names of persons present and amount you won or lost. Paper Doll doesn’t imagine that the personality attributes for gambling aficionados and those for detailed diary-keepers would dovetail, but hey, I’m just here for the organizing.
Un-reimbursed employee expenses may include expenses for your vehicle or for travel, meals, entertainment or even client gifts. Unfortunately, you have to itemize (i.e., not take the Standard Deduction) and your combined itemized expenses must equal 2.5% or more of your adjusted gross income. Since you have no way of knowing in January what kinds of expenses your employer might force you to rack up in July, start maintaining a folder for these records right away.
Tips–Do you work in the food industry or a personal service profession where you receive tips? The IRS expects you to keep track of and report what you’ve made. They’ve even created form 4070A with lines for each day of the month–print 12 of them–to help you maintain your record of the tips you took in and what you were required to “tip out” to other support staff members (like bus boys, shampooers, etc.).
Proof of payment for jury duty–Most people get less than $9/day (though some municipalities are now paying up to $40/day), but since it’s reported to the government, you need to keep your records, too, so you can report it as miscellaneous income. If your employers required you to turn your jury duty payments over them, you’ll want records so you can request an adjustment to reduce your AGI.
Self-employed/small business expenses–If you own your own business, Paper Doll hopes you have a carefully-created filing system for all your business-related expenses. But just in case, next week’s post will be all for you, reviewing the kinds of records you need to maintain to ease the small business tax-time burden.
Remember, Paper Doll is a professional organizer. In the parlance of the web, IANAA (I am not an accountant) and IANYA (I am not your accountant). For tax-related questions, please contact an authorized tax preparation specialist or financial planner.
Organizing Your Tax Paperwork–Part 1: The Taxman, the Eggman, the Walrus and You
If you try to sit, I’ll tax your seat.
If you get too cold, I’ll tax the heat.
If you take a walk, I’ll tax your feet.
~ “Taxman”, The Beatles
Sitting on a cornflake, waiting for the van to come.
Corporation T-shirt, stupid bloody Tuesday.
Man, you been a naughty boy, you let your face grow long.
I am the eggman, they are the eggmen.
I am the walrus, goo goo g’joob.
~ “I Am The Walrus”, The Beatles
If you’ve ever sat down to do your own taxes without any advanced preparation, you’ve probably been babbling the nonsensical “goo goo g’joob” into the wee hours of the morning. (Perhaps crumpled tax forms sound like Corn Flakes when you sit on them? Oh, those Beatles!)
Organizing your paperwork for tax season can be easy, if you’ve been filing away your paperwork all year as it’s come into your life, and if you have a handle on what papers should already have arrived. If not, you might find yourself procrastinating on what could be profitable (if you’re expecting a tax refund) or at least insightful (because the sooner you know how much you owe, the more time you’ll have to amass it before April 15th).
Different types have different approaches to the coming tax season. For example, if you’ve practically memorized IRS Publication 552 and know the differences between Forms 5498 and 5754, you’re the Taxman. Maybe you already work for the IRS, or are a certified public accountant, or feel about schedules and forms and worksheets (Oh, my!) the way others feel about Facebook or I feel about a certain Mr. Clooney.
If you sell services or products, like ovoid chicken byproducts, for example, you are the Eggman. You’re a self-employed small business owner, and we will cover your tax paperwork issues in a post two weeks from now.
If you look decidedly like Wilford Brimley:
but are not actually human, then you are the Walrus, and it’s highly likely that you don’t owe any taxes this year. (Note: if you are a walrus, but work in the performing arts sector and have received a W-2 or 1099, please see your accountant for further instructions.)
In this post, we will cover the information returns, forms you should have received (or will soon be receiving) that inform you (and the IRS) what monies you have received, and in some cases, paid. These documents are essential to filling out your taxes, which is why I frequently advise having a Tax Prep hanging folder (with interior folders for informational documents like these, as well as charitable and medical receipts, which will be covered in next week’s post).
Have you noticed if you’ve received all your forms? All W-2s and most 1099s are normally required to be mailed by the last day of January, but because January ended on a Sunday this year, companies and individuals had an extra day. Although employers had to deliver or mail W-2s to employees by February 1st, they have until March 1st to postmark copies to the IRS.
Note also that financial institutions have until February 16, 2010 to mail 1099-B forms (Proceeds from Broker and Barter Exchange Transactions), relating to the sales of stocks, bonds, and mutual funds. 1099-S forms, related to real estate transactions, also have the 2/16/10 mail deadline, so watch your mailbox for these items.
Each taxpayer’s situation is unique, but the following are the most common types of information return forms used by individuals (i.e., not those involving trusts, estates or corporations).
W-2
This is the Wage and Tax Statement form your employer gives you (and sends to the IRS) to delineate how much you were paid, and, if applicable, how much money was withheld from you and paid to the federal and/or state governments for taxes and FICA (Social Security and Medicare). Your W-2 may also indicate other values withheld from your check, including regular donations to the United Way, payroll purchases of stock options or savings bonds, etc.
Don’t confuse the W-4 (that tells your employer how much tax to withhold) with the W-2. Yes, the IRS number system is weird–you get a “4” when you start a job or change your deductions, but a “2” at the end of each year’s performance of that job…not at all in numerical order.
There are multiple copies of any one W-2. Employers submit copy A directly to the Social Security Administration and keep copy D for their records. You get to keep copies B (to send with your federal tax return) and C (to keep for your records), as well as copies 1 and 2 to file with any applicable state or local tax authorities. Paper Doll maintains that it’s awfully disorganized to change nomenclature in the middle of a sequence from letters to numbers.
If you haven’t received your W-2s by February 15, 2010, contact your payroll or human resources department immediately. W-2s may be given directly to employees at work, or might be mailed to the address of residence you listed on your W-4. Also consider:
- Did you change employers this year? If you had more than one job in 2009, be sure that you have received W-2s from each employer. If you received a promotion or moved laterally, you’ll still only receive one W-2 from each employer, not one per position.
- Did you change addresses? There’s only so much a former employer will do to track you down to give you your W-2. Remember, just because you don’t have your W-2 does not mean the IRS doesn’t know what you earned–remember Copy A!
If former employers drag their feet about sending a W-2, or if a past employer has gone out of business, and your W-2 hasn’t shown up by March, contact the IRS at 800-829-1040. They’ll run interference and also send you a form 4852, which you can fill out in lieu of one supplied by your pokey old company.
1099
There’s not just one type of 1099. In fact, there make a whole bunch of 1099s, to reflect the myriad types of financial transactions of which you might have been a part. For example:
1099-MISC is what you may receive from a client/customer if you were an independent contractor (i.e., self-employed) or received any kind of revenue for doing work when you were not actually considered an employee. Individuals and companies are only required to submit 1099-MISC forms to you and the IRS if you earned $600 or more from them during a calendar year. Please note that even if someone paid you for doing work as an independent contractor, they may not know they should be sending you a 1099-MISC. This is why, if you are self-employed or irregularly-employed, it’s still vital to keep track of your incoming revenue for yourself. (We’ll discuss this more two posts from now. I bet you can’t wait!)
1099-INT reflects the interest income you receive from interest-bearing savings and checking accounts, money market bank accounts, Certificates of Deposit, and other accounts that pay interest. This form also notes whether foreign or U.S. taxes were already withheld and if there were any penalties assigned for early withdrawal from an interest-bearing account.
1099-DIV indicates the dividends or capital gains you received as an investor. You would receive this from a broker, mutual fund company or other type of investment company. You may not have actually received dividend payments; check your account history, as you might be registered in a DRIP, or direct re-investment plan where dividends are invested back into the stock.
Unlike W-2s, which normally come in separate envelopes with nothing but a cover letter to obscure them from view, 1099s aren’t always so easy to find. Very often, instead of sending a 1099 in a separate envelope, a bank or brokerage may attach a tiny 1099 to the bottom of a fourth quarter statement, divided only from the actual statement by a faint perforation. Keep your eyes open!
Some internet-only banks, like ING, only provide 1099-INTs digitally. By now, you should have received an email from your online bank, telling you how and where to locate your online 1099. To avoid any kind of phishing scams, log into your online bank account directly (instead of clicking on any email links) to access 1099s as downloadable, printable PDFs.
If you haven’t received your 1099’s by the end of February (or your 1099-B or 1099-S by March 15th), contact the financial institution directly. If they do not respond to your inquiries in a timely manner, you have a few alternatives.
For most 1099s, if you can gather the information via another method (i.e., year-end statements for bank and brokerage accounts, copies of checks deposited as an independent contractor, etc.) and are reasonably sure that your own paperwork is accurate, substitute that to fill out your tax forms.
However, 1099-R forms must be attached to your tax return because they indicate when income tax has been withheld. If you can’t get anyone to help you acquire your 1099-R, call the IRS at 800-829-1040, as described above for W-2s, and they will send you a substitute form 4852 to use in lieu of an official 1099-R.
1098
1098s are not merely 1099s with low-self-esteem, nor have they sworn off carbs. This form, the Mortgage Interest Statement, reflects the interest you paid on your household mortgage, which is generally deductible on your federal taxes. If you paid more than $600 in mortgage interest last year, your mortgage holder should send you (and the IRS) a 1098.
Your 1098 doesn’t just reflect mortgage interest paid; it also delineates whether you paid PMI, or private mortgage insurance, which can be up to 100% deductible if your adjusted gross income is less than $100,000. (Check with your CPA; I’m just here to give organizing advice.)
There are also sub-types of 1098s. For example, you might receive a 1098-C from a charitable organization if you donated a car, boat or airplane. A college might provide you with a 1098-T to indicate you paid tuition, or a lender might send a 1098-E to show you’ve paid student loan interest.
If you have not yet received a 1098, don’t panic. You’re not required to send 1098s to the IRS with your return. However, it is important that you have accurate information to submit on your return. So, are you missing a:
–1098 for mortgage interest? Contact your mortgage holder by phone to request documentation of the mortgage interest you’ve paid; if possible, request that they fax the figures to you so you have something in writing right away. Email, however, is not a safe medium for transmitting documentation, especially as your file likely includes your Social Security number.
–1098-E for educational interest? Contact the lender or your school’s student aid office. Note that not all educational interest is deductible. (And if you have a campus ID card that can be used as a charge card, the interest you pay on a balance carried for late-night snack food is definitely not deductible.)
–1098-T for tuition paid? Contact your school’s administrative business office. If you (or your child) live on campus, an in-person visit will likely achieve quicker satisfaction than a phone call or fax, as ID can be verified more quickly and it’s harder for staffers to ignore someone hovering around their desk (vs. an email, fax or voicemail).
These are just a few of the informational forms that individuals are most likely to receive in support of completing tax returns. If your personal financial dealings are complex, you might find it useful to peruse this lengthy list and description of all tax-related forms…or hire a professional.
Next week, we’ll look in-depth at all the supporting materials (other than information return forms) that taxpayers should be collecting and organizing to help ease the strain of tax time…so you don’t find yourself sitting on a Corn Flake in the wee hours of April 15th.
Playing Your Cards Right: How The CARD Act Helps Organize Your Finances
By the beginning of February, most consumers have the doldrums. New Year’s resolutions to organize finances have faded in the shadow of piles of credit card statement reflecting holiday excesses. This February, however, brings some good news, as most of the elements of the Credit Card Accountability, Responsibility and Disclosure Act of 2009, designed to bring a little bit of fairness to credit card practices, rolls into place as of 2/22/2010.
A few of the provisions actually went into effect last August, just three months after Congress passed the law. As of last summer, lenders are now required to mail credit card statements 21 days before the payment is due. You might have noticed a lead-time creep over the past few years, when companies were only required to mail statements 14 days prior to due dates. With weekends and national holidays in the mix, it gave very little turnaround time for struggling (or disorganized) consumers.
Another provision that went into effect last August was requiring 45 days advanced notice of changes to interest rates and fees. Credit card companies used to only have to give only 15 days of advanced notice before raising interest rates.
What do the new changes mean for you?
Let’s Talk About Rates, Baby!
Perhaps one of the biggest boons for consumers is the new provision that credit card issuers can’t increase rates on existing balances unless:
–payments are more than 60 days late
–the teaser rate has expired
–your card has a variable rate tied to a financial index that has increased
Until now, when your credit card rate changed, it would mean increasing the interest rates on your pre-existing balance–a retroactive rate hike! It would be like the clerk from the grocery store showing up at your house, demanding more money for the pint of Ben & Jerry’s you bought the prior night.
Sure, we all know that the best thing is to never carry a credit card balance, but this is the real world and Paper Doll realizes that some of you do carry balances, that there are no unicorns and that George Clooney hasn’t called to make sure I’ve saved Valentine’s Day for him. (Sigh…)
If you’re carrying a credit card balance at a non-teaser fixed rate and you’re keeping your payments current, your issuer can’t raise the rate on that balance. And, except for expiring teaser rates, credit card issuers can’t increase the interest rate on new purchases in the first year you hold a card.
Note, however, that the interest rates on all future purchases can increase (as long as the issuer abides by the other rules, as noted throughout this post).
Don’t Be A Tease
In the past, credit card company teaser rates (those low, low rates they dangle to get you to sign up?) sometimes lasted as few as five or six weeks! Under the CARD Act, teaser rates must stay in effect for at least six months. No more sneaky teases!
It’s a Whole New Universe!
Had you ever heard of universal default? That was the policy that credit card companies could (and would) raise your rates if they learned that you had been late or otherwise defaulted on terms of other accounts unrelated to their own company. Rates of 6.9% had previously shot up to 29.9% on Card A because a person had been reported late (even if reported in error) on Card B operated by another company. Now, the CARD Act has eliminated universal default, bringing things back down to Earth.
Stop Spinning Your Wheels–No More Double-Cycle Billing
Another sneaky method some credit card companies have used is two-cycle billing, where issuers were averaging daily balances from the previous billing cycle because carrying a balance eliminates a cardholder’s right to a grace period. Yes, if you had a card with two-cycle billing (I’m looking at you, DiscoverCard!), you were paying interest on debt you’d already paid! The CARD Act does away with two-cycle billing.
In The Interest of Full Disclosure
Savvy Paper Doll readers certainly already know that if one only pays the “minimum” payment required by a credit card company, it can take years of extra payments (and extra interest) to pay off credit card debt. However, many consumers don’t realize this, and they certainly don’t realize the extent to which their payments for that fancy dinner or fuzzy sweater will be drawn out over time. The CARD Act requires that monthly credit card statements indicate how long it will take to pay off a balance (and the total cost, including all that pesky interest) if you make only minimum payments.
Although this wasn’t required to go into effect until February 22nd, Citi and other card issuers have already started sending the new statements. One consumer with a balance of slightly less than $2700 was shocked to see, in black and white, that paying only the minimum would take 16 years and almost another $2700 in interest! Paper Doll believes the CARD Act disclosures will have a profound impact on the speed with which consumers who are able to pay more towards balances will do so.
Over The Top
In the past, credit card companies could automatically charge you a fee if you went over your credit limit. You’d probably figure that if you have a $5000 credit limit on a card, if your current purchase would put you over the limit, the store clerk would lean over quietly and say “Pardon me, but there seems to be a problem. Perhaps we should use another card.” But nooooooo. Credit card companies apparently believed that the huge humiliation (note my dripping sarcasm?) of such an experience was preferable to huge fees tacked on to an already over-limit card, fees which would then have interest charged on them.
Once the CARD Act goes into effect, over limit fees can only be applied to your purchases if you opt in and give prior approval to the credit card company.
Ready, Fire, Aim: Apply Payments Where They Should Go
As a professional organizer, I’ve had to show clients how they were getting raked over the coals by credit card companies in unexpected ways. Most never knew that if they had a promotional rate (0%, 1.9%, etc.) for a balance transfer to a card that already had a balance, or continued to use that card after doing a balance transfer, that the credit card company wasn’t applying the payments as they assumed. Credit card companies generally applied payments to the lowest interest rate balances, allowing higher interest rate balances to pile up.
Let’s say you transferred a balance of $10,000 to your card, using a 0% promotion. Plus the 3% or 4% processing fee. That fee, plus the transferred amount, would be at 0% until the rate expired. Let’s say you then charged $300 on that same card. Even if you turned around and paid back $300, the $300 would be applied towards your balance with a 0% rate, while your $300 purchase rate balance would sit there, racking up interest, until the original $10,000 was paid off. And it was all explained in the tiny legalese that few consumers ever read.
Now, under the CARD Act, payments in excess of that sneaky old “minimum payment” must be applied against the balance with the highest interest rate first, and then to any other balances, in descending order according to interest rate, yielding impressive long-term consumer savings.
Gimme A Call
If travel or disorganization might keep you from mailing a payment in time to reach the card issuer by deadline, you have electronic alternatives. Online bill-payment from your bank (or right at your credit card company’s site) can give you last minute breathing room. But what if you’re traveling and have no access to Wi-Fi? What if you get hit by a wacky winter storm and have no electricity, let alone internet access? There’s always the phone! However, lots of credit card companies have charged a convenience fee for paying a bill by phone.
Under the CARD Act, if a credit card company does offer a pay-by-phone option, it has to be free unless you need to use a live service representative (instead of a robo-phone) to make a rush payment.
Do You Believe The Children Are Our Future?
Two other provisions will have a direct impact on the future financial health of young adults. In the past, anyone over 18 could apply for (and likely receive) a credit card without substantive proof of financial solvency. With the CARD Act:
–Applicants under 21 years of age will have to have an adult co-sign for their credit cards or otherwise provide actual proof of regular income.
–Credit card issuers will no longer be allowed to offer sign-up gifts (t-shirts, mugs, flash drives, etc.) on or near (within 1000 feet of) college campuses, or at events sponsored by colleges.
By making it less likely that college students can amass credit cards (and therefore credit card debt) as easily as they can scarf up free pizza, the next generation should be able to graduate without debilitating mounds of (non-educational) financial obligations.
A Chance for a Do-Over
One provision won’t go into effect until August 2010. With it, if consumers are assessed a penalty interest rate because of a late payment, they can reclaim that prior (lower) rate if they pay on time for six consecutive months.
Of course, these new rules mean that lenders are going to be looking for other ways to sock it to you (like charging annual fees for participation in rewards programs), so you still have to be aware and diligent when handling your finances. Be sure to:
Review your statements each month before paying & filing them away. If you use paperless billing, you’re helping the environment but you may not notice small changes if you can’t take a pen or highlighter to mark the changes. (Please, no little highlighter circles on your monitor! It will make reading future Paper Doll posts very difficult.)
Know the terms of your credit card agreement so you can quickly notice changes or errors and take advantage of opportunities:
- What is your interest rate right now?
- If you have multiple rates (due to promotions) on the same card, do you know which balances are associated with which rates?
- Are your interest rates fixed or variable?
- How long is each promotional rate is in effect? (Is it until the last calendar day of a particular month, or until the last billing date in a statement period?)
- What’s your credit limit on each card? How much of it are you using?
- Are you paying an annual fee? If so, why? Annual fees are generally for perks, so be sure that the perks are something of which you’re actually taking advantage.
- Are you earning points or miles? Have you ever used them? Check to see if you’ve earned enough to get cash back or a statement credit, which provides a better return on investment than dribbles of hard-to-redeem airline miles.
Rein in any bad habits that might negatively impact your FICO score, as we discussed previously.
Know which credit card issuers offer the best alternatives for your particular situation and spending habits. (That way, if your rates do increase, you’ll have time to evaluate the best replacement card.) Do you need a low-interest card? One that offers a particular type of rewards? Peruse sites like BillShrink.com and BankRate.com to analyze your options and search by card issuer, credit score level or card type.
An organized, educated consumer is a powerful force. Paper Doll readers, flex your muscles!
Get Organized Month: Paper Control–Open Book Exam
We’re coming to the end of our month-long Get Organized Month course on paper control. In our first semester, we reviewed the basics, including identifying and evaluating incoming papers (and the backlog), purging unnecessary papers, halting the influx of junk mail, credit card and marketing offers and other cluttery mail, and developing an initial system for paper management.
In our advanced semester, we offered up shredder wisdom and reviewed how to develop a digital system matched to your paper organizing system. And last week’s graduate course covered the vital topic of vital documents and creating a system for keeping you out of jail, out of unwarranted debt and off the terrorist watch list. (This advice was limited to proving identity and payment; if you’re actually a bad guy, you’re on your own.)
All of this leaves you prepared to take the open book test that is life–keeping you chaos-free in the paper department. There’s only one final lesson, with variations on a theme.
In general, I believe in filing systems using actual files. Whether you run a home business or the business of your home, papers stored vertically in file folders (in their myriad forms, from plain 1/3 cut manila folders and olive green hanging folders to brightly hued versions) give you the least expensive, most expansive, opportunity to organize your life. However, there’s a more important lesson to take than “files rule and vertical storage rocks”:
If you don’t like your system, you won’t commit to it.
Human beings are tricky; we’re not cookie cutter automatons. Some people can’t abide anything short of a Skittles “Taste the Rainbow” panoply of colors; others find the mere sight of filing cabinets to be distasteful. If you don’t like the aesthetics of your system, no matter how well it works in the abstract, you’re not going to faithfully use it. If you avoid the system, you’ll avoid the action, and your papers will continue to pile up around you. Soon your Paper Doll University diploma will be sandwiched between car wash coupons and your 1099s on the sticky kitchen counter. That won’t make anyone happy.
So, taking everything you’ve already learned in the prior coursework into account, there are variations to consider for each type of paper in your life:
REFERENCE PAPER/FILES
You’ve studied up and you know you have to have an organized way to keep your financial, legal, medical, household and personal reference files orderly so you can retrieve what you need at a moment’s notice. But the minute you read “filing”, you started to cringe.
Chance are, you don’t hate filing, just the ugly metal filing cabinets that remind you of your old corporate job or the principal’s office. There are any number of gorgeous alternatives to gunmetal grey cabinets. At one end of the design continuum, there are the colorful plastic milk crates file boxes; at the other, there are luxurious leather file boxes.
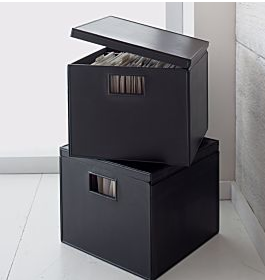
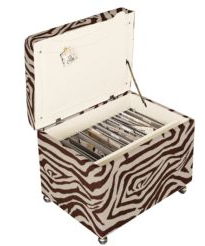
There are glorious filing cabinets designed to fit your office dcor, as well as filing-cabinet ottomans, baskets and boxes that range from quirky to CEO-chic. If you need to move your files from kitchen to home office, or home office to your studio, there are all manner of file carts for your pop-a-wheelie pleasure, like these from
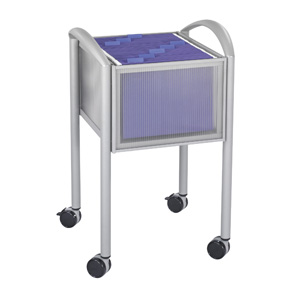 Safeco or
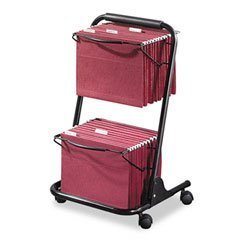 Rubbermaid.
And what if you have a perfectly good filing cabinet that just bores you to tears? There’s always the DIY approach.
(For more filing container delights, I direct you to the blog of my favorite organizational product maven, the incomparable Jeri Dansky who has her finger on the pulse of form+function magnificence.)
Of course, there’s a popular alternative to using file folders altogether: the binder. As we’ve discussed in past posts, ringed binders are especially great for keeping track of financial data like banking and investment statements, as well as recipes.
A major advantage of storing reference materials in binders is that it makes it eminently portable. If you want to carry five years of retirement investment statements to your new financial planner, a binder is far easier to tote than an overfilled folders. (As with people, folders get unwieldy with too much tonnage.) For those concerned with aesthetics, there are some very attractive pre-made binder options out there; alternatively, the plastic front/back covers and spines of most binders let you quickly decorate them by inserting photos (…even a down stock market is cheerier if George Clooney’s looking back at you) or useful information (like metric conversions for the front of your recipe binder).
The main disadvantage of binders vs. folders is added labor. To walk your fingers along file tabs until you locate the correct file into which you drop a piece of paper takes mere seconds. However, punching holes (or placing a piece of paper in a plastic sheet protector) takes longer, making people less likely to file as they go. The more the paper clutter piles up (like dishes in the sink), the more forbidding the task seems.
INCOMING PAPER
Of course, before paper can ever be filed away (or acted upon), you need to figure out what it is, and to do that, it’s best to have all the paper that enters your house or office start off in one place. If all the new mail, receipts and papers get plopped down anywhere from the couch to the top of the microwave, your system will break down before it ever gets started.
The horizontal paper gathering device is better known by its more common name: the lowly in-tray. In-trays can be plastic, metal or mesh. A dishpan from the dollar store is as unbreakable as it is unremarkable, but is great when you’re teaching the tiniest members of your household how to put papers away without concern for damage. Standard trays run the gamut from utilitarian pieces from office supply stores
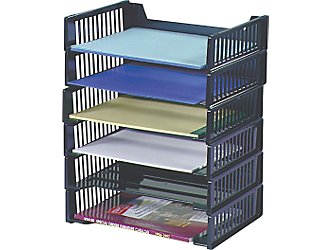 to more eclectic options
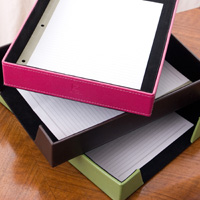 at online specialty shops (like See Jane Work), and they can all run from single-story to skyscraper style, depending on your needs.
If you’re short on flat space, incoming papers can also find a vertical home in containers as simple as those smoky plastic wall pockets outside your doctor’s examination rooms, to magnetic stainless steel and canvas options like these from the Container Store:
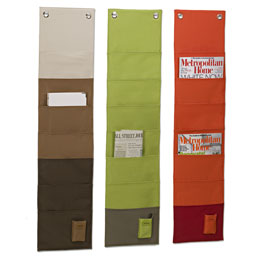
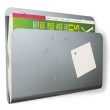 to decor-matching solutions suitable for the Colonel Mustard in the Library.
ACTION PAPER
Once papers enter your life and have been deemed worthy of avoiding the shredder, they either need be filed away (“sent home”) for reference or acted upon. Indeed, most of the paper clutter in which people drown are items that represent actions or tasks they must perform. Regular readers of this blog know how much I love tickler files
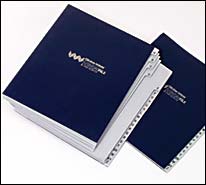
for prioritizing and easing the handling of action paper. (While I can’t say “I like them so much, I bought the company”, I can say I like them so much, I wrote a book about them!) There are multiple brands and styles of tickler files, from the portable accordion-style standard to the DIY-version you can make with 43 folders (31 for the days of the month, plus 12 for each individual month), which you can keep in a desk-top file box, either plain-jane plastic or fashion-forward. There are even vertical versions of tickler files to use a week at a time, like EZ-Pocket from OnlineOrganizing. 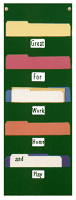
(One caveat: Slotted wooden products 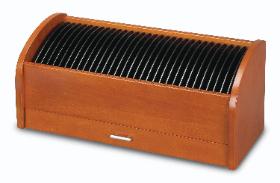 are designed for mail and are too small for action papers.)
Not everyone is keen on tickler files, however, and some people prefer to create action folders (To Read, To Write, To Call, To Pay, etc.). Unlike reference files, which are best kept corralled away from the prime real estate, action files belong where you can see them…they just shouldn’t lay flat on the desktop. Open desktop file boxes 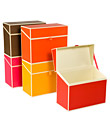 and file risers/sorters
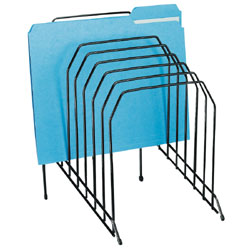 are perfect homes for these task-oriented files divided by category. (Get a riser that elevates each file progressively, like stadium seating at the movies.) However, as the these categories aren’t sorted or prioritized by date, be sure to schedule blocks of time on your calendar so your must-do items don’t languish in the folders.
TRAVELING PAPER
In addition to dealing with the incoming, action and reference paper, there’s another kind of paper that straddles all of these categories–paper that you need when you’re moving through space, time and life. Paper Doll University’s extension courses have previously covered the systems and products for dealing with personal and business papers that travel when you do:
Mobile Mavens: Keeping the Personal Paper Portable When You’re Out and About
A Culinary Model for Successful Mobile Offices
Don’t forget to keep track of the papers you need for traveling. One of our readers commented last week about losing track of vital documents before traveling, and maintaining those documents while on the move is also always a concern. I advise:
1) As soon as you receive your travel confirmations (tickets, itineraries, car/hotel reservation confirmation numbers, etc.), make sure you have everything you need (including toll-free numbers). Now that e-tickets are the norm, it’s ridiculously easy to print two copies of your itinerary or receipt and no actual ticket/boarding information.
2) Next, print two copies (oh, the trees!) or email copies to a trusted friend (or two) who is always online and available in an emergency. If you are traveling with a partner, each should keep a copy of the other’s info; also, plan to keep an extra copy of your papers in your suitcase in the event your main copy is lost during your trip, after arriving at your destination.
3a) Put travel confirmations in a poly envelope  that seals with an elastic band or snap, preferably one that is translucent so that you can place your documents in the order in which you’ll need them. Move the flight itinerary facing out the front; after you’ve used your ticket, have your rental car or hotel reservations facing the back so you can read them without evening opening the envelope.
3b) Keep tickets in the poly envelope OR in a passport/ticket wallet. Faux-classy vinyl or leather portfolios allow you to keep your passport, ticket, other ID all snugly together when you’re traveling abroad.
4) Put the poly envelope in your tickler file for the day before you’re going to travel, so you can review your documents and travel times. If you don’t use a tickler, be sure to note in your calendar where you’ve placed your tickets and paperwork. (If your office isn’t yet organized, consider putting the paperwork in your carry-on bag, so you’ll see it when you start packing for your trip.)
5) When you return from your trip, empty the poly envelope and passport/ticket wallet as part of the unpacking process. Make sure your passport and various forms of ID go back to their permanent homes when their (and your) vacation is over.
Congratulations, Paper Doll University graduates! Go forth and master your paperwork!
Get Organized Month: Paper Control Graduate Seminar–Very Important Papers
Paper Doll once found a bug.
“Eeek!”, right? Well, not exactly.
In the process of working with a client, I opened a kitchen cabinet to find a plastic zipper-locked baggie with one perfectly preserved and entirely dead insect. The baggie was nestled vertically between two straight rows of juice glasses in an otherwise perfectly arrayed cabinet. Retrieving the baggie, trying to be both delicate and jaunty, I asked my client what was up. She smiled, sighed, and said, “Well, I have to show the exterminator what I found and where, and I couldn’t figure out how to do that unless I put the bug back where I found it.”
I still recall thinking that the client would still have to remember where she’d put the baggie, and if she remembered where she put it, then she wouldn’t need the baggie there anymore. (I also remember thinking that maybe she could have taken a photo of the little creature, but perhaps her exterminator needed to do an autopsy, CSI: Kitchen-style.)
Setting aside the Kafkaesque connection of this anecdote, I think it reflects the problems many people face when they have no paper control system.
Obstacles
During the run-up to Get Organized Month, I received a mailing from Smead (one the two main filing solution bigwig companies) with some information regarding their recent survey researching people’s paper management habits. The survey included finding out where people stored their VIPs (what Paper Doll calls those very important paper documents like birth certificates and passports).
In part, the mailing said:
Under the mattress, inside shoeboxes and even in the garage are just a few of the places that people use to safeguard their personal documents — which perhaps explains why 30 percent of Americans have lost important papers….The survey asked respondents to list the most unusual place where important documents are hidden and found that 10 percent of Americans keep personal documents in an underwear drawer and six percent use shoeboxes. Respondents also listed kitchen cupboards, the garage and even under the mattress as a place to store personal papers.
Like my client with the baggied bug, when not entirely sure where papers should go, people tend to put things where they feel they will be kept safe (underwear drawers or under mattresses) or where they will be seen often enough (kitchen cabinets) to be remembered. Apparently the recent news story about the woman who lost her hidden-in-a-mattress life savings is not enough to dissuade people from valuing hidden over secure.
The survey found that upwards of 30% of Americans had reporting losing an “important document”, and acknowledged that replacing those documents took multiple days. Paper Doll has previously reported on the procedures for replacing lost vital documents, including birth certificates, Social Security cards and passports. If you’ve had to follow those steps, you can verify that it’s certainly easier to put a fool-proof system in place than to feel foolish, wasting time in-line or on the phone, trying to replace mortgage paperwork that you “just know is here somewhere”.
Smead’s survey asked people why they hadn’t gotten their important personal documents organized. A striking 40% of those surveyed mentioned that they lacked the time or were overwhelmed by the process of getting these documents organized. As any professional organizer, and anyone who has lived through a natural or other disaster, would be quick to tell those respondents, trying to recover from a catastrophe without easy access to one’s most important papers is much more overwhelming!
Survey respondents also told interviewers that not knowing what papers they could get rid of, and what was important to keep, prevented them from moving forward. (The anxiety over making a mistake on this front is easily solved with a records retention schedule or, ahem, my Do I Have To Keep This Piece of Paper?).
Another reason respondents gave for having no organizing system for their most important papers was that they simply didn’t know where to start. If only I had been able to piggyback on each of these survey questions, I’d have taken these people by the hand and assured them that it simply doesn’t matter where you start, as long as you get started, because you never know when you’ll have an urgent need for your vital documents.
Solutions
When they sent out their survey results, Smead presented their three-part approach to organizing vital papers, a philosophy with which I think all professional organizers would agree:
- Keep it Simple
- Keep it Safe
- Keep it Handy
Keeping it simple starts with…just getting started. Maybe you already know that your passport is in the bottom of your carry-on bag. Perhaps you’re pretty sure your firstborn’s Social Security card is paper-clipped to those little inky hospital-record footprints, tucked in the bottom of the long-unused changing table. If so, you’re ahead of the game.
However, if you’re just trying to imagine what documents are important, get a head start by making a list based the items discussed in these past posts:
Top 10 Vital Documents–Do You Know Where Your VIPs Are?
More VIPs–Very Important Papers Beyond The Top 10
I Fought The Law…and the Paperwork Won
Once you’ve made your list, visit all the usual suspect venues in your home until you’ve found as many VIPs as you can. When you’ve given up on locating something apparently lost, or realize there’s a document you never actually had, set about acquiring replacements. But you don’t need to wait until you have everything before you organize your documents.
Keeping it safe means creating a home that will protect your VIPs from natural and other disasters, as well as from theft and even the prying eyes of snooping household visitors. Often, people think this means getting a bank safe deposit box, but that’s not necessarily the case. In times of natural disasters, banks are often closed or at least inaccessible at the very time you will need documentation for proof of identity, ownership, insurance, etc. If you do keep originals in the safe deposit box, be sure to have accessible photocopies, especially for insurance policies and property deeds, in your file system.
A fireproof, waterproof safe or file box, one designed specifically to hold hanging files, and preferably one that is light enough to carry, should be adequate to protect your most vital documents from the elements (and the bad guys).
Keeping it handy means that accessibility is key. If you create a fabulous file system for your reference files and vital documents, but bury it in the back of your closet so that you literally have to duck under old coats to retrieve files, you’re likely to find every excuse to avoid returning them once you’ve used them or filing newly-acquired vital documents. If the home for your VIPs is inconvenient, your passport probably won’t make it back home after a vacation, your Social Security card will languish on your desk after you’ve filed for benefits, and your kids’ birth certificates will stay piled up with the school registration paperwork.
Conversely, there are ways of keeping your documents a little too handy. I’ve seen people keep a desktop file box in the kitchen with all of their essential documents. Security issues aside, that might be fine if there’s a built-in desk area in a kitchen, but an open-top file box on or next to the stove, sitting out on the counter or balancing on a kitchen chair is an invitation to getting your vital documents overly toasted or soaked with Fruit-Loopy milk. Keep your file system somewhere far away from direct heat, moisture, the not-so-nimble fingers of toddlers (and their crayons) and family pets.
So…
- Collect your very important documents from the four corners of the Earth. (OK, from around your home, and perhaps your parents or in-laws’ home.)
- Review the lists provided above to make sure you haven’t missed anything vital.
- Label a few simple file folders
 (or, if you’re super-short on time, just put them all in a Kraft envelope
 and label it Vital Documents).
- Create a designated home for your VIPs.
- Document (preferably in the computer) what records and paperes you own and where they’re located (so you won’t run to the bank when your passport is actually in your file box).
Share Your Story:
The survey results showed that most Americans rank their Social Security card as their most important personal document. The breakdown:
47% Social Security Card
22% Birth Certificates (their own and those of family members)
11% Ownership documents, including deeds, titles and stock certificates
10.5% Passport
9.9% Wills
Readers, what is your most important personal document? If missing, what VIP item would cause you the most distress? And perhaps, most importantly, do you know where that item is right now?
Do you have a fun story about losing (and hopefully finding) your papers, or about storing them in unusual places? Please share your tales in the comment section…once you’ve gone to check to make sure everything is where it should be.
Follow Me